apple pay casino
Apple Pay Casino: Wallet Deposits and Where Withdrawals Go
A deposit that clears in seconds and a payout that still travels by card: the model below prices both legs of an Apple Pay session.
The shortlist, before the detail
The board below carries this month's featured offers with their headline terms. The prose that follows models offers of this kind and never repeats those figures; the operator's own page is always the binding version.
Roulette King picks
Top roulette offers this month
The shortlist first, then the arithmetic. Four featured packages carry the headline terms below; the rest of the page models what offers of this kind usually cost and what a licence would have added.
Terms checked at the October 2026 review · 18+ · T&Cs apply. Offers move often: the operator’s own page is always the binding version.
- 1
 Night Luck82/100Casino welcome bonus 805% up to €6,400 + 280 FS
- MuchBetter · VISA · Apple Pay
- Crypto welcome 140% up to 1,600 USDT
- VIP pack 800% up to €14,500
Visit siteNight Luck18+ · T&Cs apply - 2
 EliteSpin80/100Welcome bonus €/£5,000 + 500 FS
- MuchBetter · NETELLER · MasterCard
- Lootboxes up to €/£20,000 or 500 FS
- BGaming festival: €80,000 prize pool
Visit siteEliteSpin18+ · T&Cs apply - 3
 Winbeast78/100Welcome pack €5,000 + 500 FS + €650 free bet
- MasterCard · Litecoin · MuchBetter
- Code FORTUNE: wheel on €40+ deposits
- Monday boost: 40% up to €300 (BOOST1)
Visit siteWinbeast18+ · T&Cs apply - 4
 Betportal75/100Welcome package 300% up to €/£1,000 + 150 FS
- Trustly · Bitcoin · Bank transfer
- 1st deposit: 150% up to €/£500 + 100 FS
- 2nd deposit: 100% up to €/£300 + 50 FS
Visit siteBetportal18+ · T&Cs apply
Placements on this board are paid, and the order is part of that arrangement. Featured brands hold no UK Gambling Commission licence, so GamStop, independent dispute resolution and segregated-funds rules do not reach them. Gambling can be addictive. Play responsibly. How we are paid.
How an Apple Pay deposit actually works
A ten pound deposit at an Apple Pay casino settles in roughly five to thirty seconds: double press the side button, glance at the camera, hold the phone near the reader, done. There are no card numbers to type, no code arriving by text, no bank page loading in a separate tab. That speed is the whole appeal of the rail, and it comes from a piece of engineering worth understanding before the first deposit, because the same engineering explains why the exit leg of the session behaves so differently from the entrance.
Under the bonnet, Apple Pay is not a purse of money. It is a tokenised wallet riding on a debit card. When a card is added, the device stores a device account number, a stand-in token, and keeps the real card number in a secure element that neither the user nor the casino ever sees. At the till, the phone transmits the token plus a dynamic security code that changes with every transaction. The casino's bank receives a payment that looks, settles and disputes like an ordinary card payment.
For the cashier, that means a wallet deposit is a card deposit wearing a mask. It clears on the card networks, it shows on the bank statement under the operator's merchant name, and the limits attached to it usually mirror the debit card underneath rather than the phone. Nothing is topped up in advance, so there is no wallet balance to manage, and no second balance to forget about when the session ends.
Seconds in, working days out
The asymmetry between the two legs is not a quirk of any one cashier; it is built into the rail. A payment token is a one-way credential, minted for the device and meant for spending. Nothing equivalent exists for paying back to the phone, so a withdrawal cannot ride the token in reverse. Instead, the payout is pushed to the underlying debit card, and from there it runs at ordinary card payout speed, behind every other withdrawal in the operator's queue.
The model on this page prices the session as two legs and two fallbacks. The deposit leg is counted in seconds. The payout leg back to the debit card is modelled at one to three working days, which is the standard window when the payout queue and bank clearing are both running normally and no manual check is raised. Where a separate e-wallet has been verified on the account beforehand, an exit through that wallet is modelled at under 24 hours. A triggered document check adds its own day or three. The assumptions column matters more than the headline times, because each assumption changes what the figure means.
| Leg | Route taken | Modelled time | Assumption behind the figure |
|---|---|---|---|
| Deposit leg | Tokenised wallet on top of a debit card | 5 to 30 seconds | Card already in the wallet, device unlocked, cashier accepts the rail |
| Payout leg | Back to the underlying debit card | 1 to 3 working days | Standard payout queue plus bank clearing, no manual checks raised |
| E-wallet exit, where verified | Separate e-wallet set up on the account | Under 24 hours | Wallet verified before the withdrawal, not created at the moment of need |
| Manual review, if triggered | Document checks before any payout moves | Adds 24 to 72 hours | Name or address mismatch, or a first payout above an internal threshold |
Two readings fall out of the table. First, the slow leg is not the wallet's fault; it is the shape of card payouts everywhere. Second, the only reliably fast exit is a verified e-wallet, and verification is a before-the-fact job: a wallet created during a withdrawal request tends to inherit the same checks as the card route. Anyone who cares about the return journey sets the exit up on day one, funds it once with a small deposit, and leaves it dormant until it is needed.
Bonus eligibility when the wallet pays
Wallet deposits carry one quirk that has caught out plenty of players: eligibility. A generation of welcome offers was written to exclude certain e-wallets, because separate wallets made it easy to move money in and straight back out. Apple Pay sits awkwardly in that tradition. Because it settles as an ordinary card payment, many cashiers treat it as a debit deposit and let it count toward offers in full. Some, though, list it among excluded methods, and the exclusion bites at the moment of deposit: the money lands, the bonus never credits, and the offer is spent.
The practical model is a two-line check. If the payments clause of an offer does not mention wallets at all, a wallet deposit counts. If the clause names Apple Pay or wallets generally as excluded, and the bonus matters, the deposit goes in by card instead. And if no bonus is wanted, a wallet deposit is arguably the cleaner tool, because the balance arrives with no strings attached and can be withdrawn without meeting anybody's multiplier.
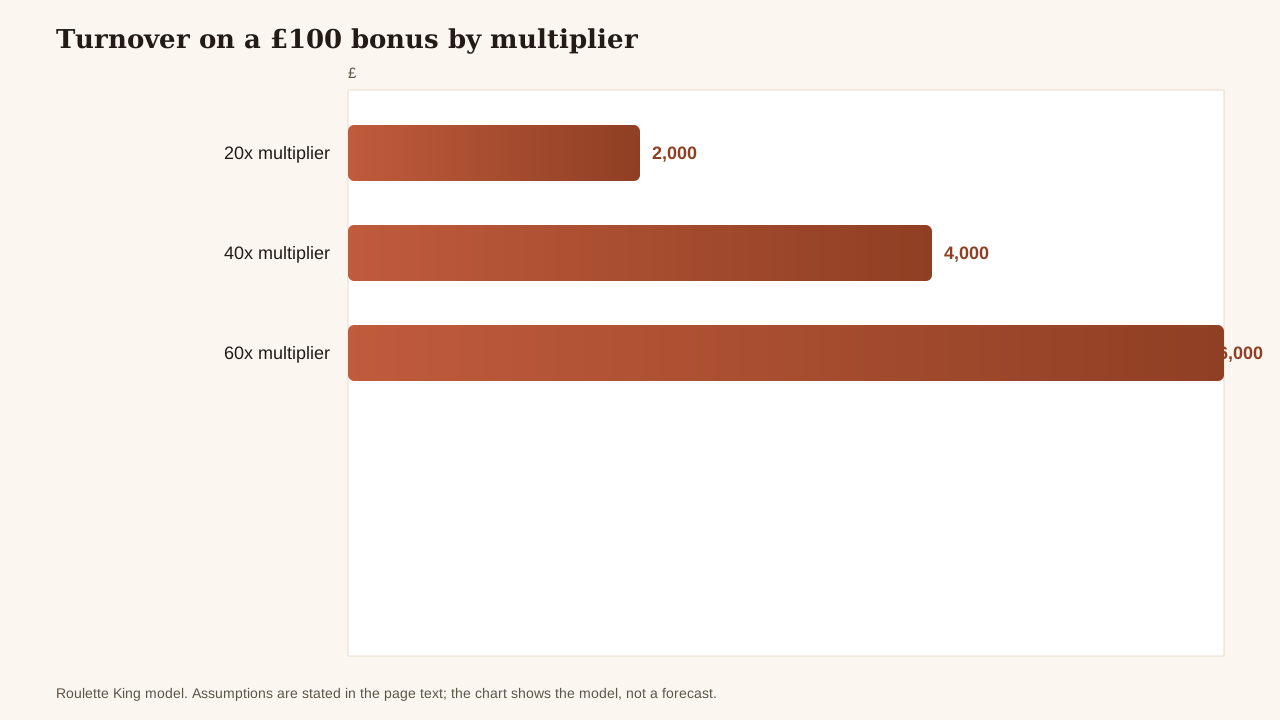
The reason to take eligibility seriously is arithmetic rather than taste. A credited bonus is not extra money; it is a turnover obligation with a deadline. The chart prices that obligation for a £100 bonus at three multipliers, applied to the bonus alone: £2,000 of turnover at 20x, £4,000 at 40x, and £6,000 at 60x. The middle figure is the working default here, because the model takes forty times, and forty times is what this part of the market typically asks for. The gap between the first and third bars is the difference between a fortnight of casual play and a month of grinding.
Running the wagering arithmetic
One worked example fixes the method. Suppose a £40 deposit brings a £40 bonus, the terms apply the multiplier to the bonus alone, and the multiplier is forty. Turnover is 40 times £40, which is £1,600. At an average stake of £2 on an even-money roulette table, that is 800 spins; at £5 a spin it is 320. Cost enters through the house edge: £1,600 of single-zero roulette turnover carries an expected cost of about £43 at 2.7 per cent, while the same turnover on a low-edge blackjack game would cost nearer £8, if tables counted in full, which many offers prevent by weighting table games at a tenth or less.
Wagering calculator
Turnover before withdrawal, modelled from the bonus and the multiple the terms set.
Model illustration with stated inputs; the terms of a specific offer always override a model.
The calculator runs that arithmetic in either direction: enter a bonus and a multiplier to see the turnover, or enter a turnover and a stake to see the spin count implied. Change one assumption and the picture moves quickly. Apply the multiplier to deposit plus bonus and the £1,600 example doubles to £3,200. Drop the stake to £1 and the spin count doubles to 1,600, which at eight seconds a spin is roughly three and a half hours of continuous play. None of these figures predicts an outcome; they price the workload, which is the only part of a bonus a player actually controls.
Verification around the card
Tokenisation hides a card number; it does not hide a person. The checks attach to the account rather than the payment method, which means the name on the Apple ID should match the name on the underlying card, because once verification begins the casino sees the card, not the token. A wallet does not create a separate identity. It is simply the newest mask over the same debit card that will eventually receive the payout.
In the model, the first payout above a modest threshold triggers a standard pack: photo identification, a proof of address dated within the last three months, occasionally a photograph of the card itself with the middle digits covered. Clean files clear in a day or two; mismatches stretch the 24 to 72 hour review window from the table earlier toward its outer edge. Two habits keep files clean: one card in the wallet, used consistently, and a name spelled in the wallet exactly as the bank spells it.
It is worth saying plainly what verification is for. It exists to keep other people's money out of the account, to enforce age limits, and to make sure payouts travel to the person who deposited. A declined or delayed check is not a puzzle to work around; it is resolved by sending the documents requested. Anything advertised as a shortcut around those checks is not a shortcut, it is a warning.
What the whole session costs
The direct fees are, in the model, zero. Apple charges consumers nothing for the wallet, and cashiers at this end of the market typically charge nothing for deposits made with it, while debit card payouts are commonly free as well. The card underneath has to be a debit card, since gambling on credit has been off the menu in Britain since April 2020. The rail itself, in short, is not where the money goes.
The real cost is the expected house edge on whatever turnover the session generates, plus the value of time on the return leg. A session that turns over £1,000 on single-zero roulette carries an expected cost of about £27 at a 2.7 per cent edge. The same turnover on slots at 4 per cent would be £40; the same money on a 0.5 per cent blackjack table, where the offer allows it, would be £5. Those are modelled averages over large samples, not predictions for an evening, but they are the honest price list of the games.
Time has a price too, though it is harder to see. A payout that arrives on working day three rather than inside 24 hours is a day of temptation to reverse it, and reversal is where disciplined sessions go to die. Pricing the exit means choosing the slowest acceptable rail deliberately: a card payout for sums that will not be missed, a verified e-wallet for sums that might be wanted back quickly. The cost of the whole session, then, is a few seconds of deposit convenience, an expected edge in the tens of pounds, and a waiting game on the way out.
Reading a cashier before you fund it
A cashier can be read in ninety seconds, and the reading is mostly about exits. Does the wallet appear at deposit only, with withdrawals routed back to the debit card? Which other rails are listed for payouts, and are e-wallets among them? What are the minimums, the upper limits per transaction, and any fees on the withdrawal side? Do wallet deposits count toward offers, or sit inside an exclusion clause? Five honest answers describe the payment experience better than any lobby screenshot.
The comparison table that follows lines up familiar names by licence, market focus and reputation, with the protections a UK licence carries alongside. It is a map of the market's shape rather than a verdict on any single row, because payout speed follows the exit rail chosen and the verification file built, not the name on the door.
| Casino | Licence | Market focus | What it is known for | UK protections |
|---|---|---|---|---|
| MrQ | UKGC licensed | Mobile-led brand | A mobile-led site that puts the wallet button at the front of the cashier | GamStop, independent ADR, segregated funds |
| LeoVegas | UKGC licensed | Mobile-first casino | A wide roulette lobby with wallet deposits built for phone screens | GamStop, independent ADR, segregated funds |
| Betway | UKGC licensed | Global bookmaker | Polished apps and a cashier that leads with wallet payments | GamStop, independent ADR, segregated funds |
| Virgin Games | UKGC licensed | Games-led brand | Wallet rails and quick deposit menus across a games-first lobby | GamStop, independent ADR, segregated funds |
| Sky Vegas | UKGC licensed | Games-led brand | Instant-play tables and low entry stakes | GamStop, independent ADR, segregated funds |
| JackpotJoy | UKGC licensed | Games brand | Daily promotions and wallet deposits on a long-running site | GamStop, independent ADR, segregated funds |
| 32Red | UKGC licensed | Long-standing casino brand | A compact cashier with wallet options and few surprises | GamStop, independent ADR, segregated funds |
| Unibet | UKGC licensed | European bookmaker roots | A clean lobby with a broad deposit range | GamStop, independent ADR, segregated funds |
| Pub Casino | UKGC licensed | UK brand | A simple cashier with phone-first flows | GamStop, independent ADR, segregated funds |
| Dream Vegas | UKGC licensed | Licensed casino | Large matched bonuses with the terms stated up front | GamStop, independent ADR, segregated funds |
| Kinghills | No UK licence | Offshore-facing casino | Big headline matches and card-based cashiers | None of the UK protections |
| Goldenbet | No UK licence | Offshore-facing casino | A sportsbook and casino under one roof | None of the UK protections |
Read the licence column first, because everything else is decoration by comparison. Every licensed row answers to the same regulator, sits inside the same self-exclusion scheme and carries the same access to independent dispute resolution, whether the lobby is aimed at phones, tables or sportsbooks. The rows without a UK licence are a different kind of proposition altogether: big headline matches and card-based cashiers, with none of the toolkit that a licence compels, and a disagreement about a payout that has nowhere formal to go. Reputation, in the known-for column, describes convenience and character, and none of it substitutes for the protections column.
What the licence buys you
A licence from the UK Gambling Commission is a bundle of specific, enforceable promises. It means the operator must integrate GamStop, the national self-exclusion scheme, so that one registration excludes a person from every UK-licensed site for the chosen term. It means customer funds are held in segregated accounts, protected against the operator's insolvency to a declared standard. It means the operator belongs to an independent alternative dispute resolution (ADR) service, so a disagreement over a payout can be taken, free of charge, to an adjudicator whose decision the operator has agreed to honour.
It also means a regulator who acts on complaints: the Commission fines, suspends and revokes licences, publishes what it finds, and expects operators to resolve complaints properly before the ADR stage. None of this is ornamental. Each piece exists because, at some point, somebody needed it and did not have it.
Offers of the offshore-facing kind carry none of it. No self-exclusion coverage, no ADR scheme, no segregated funds requirement, and no regulator with power over the operator; if a payout is refused, the recourse is whatever the operator's own goodwill provides. That is the honest price of those lobbies, and it is a price paid precisely when things have already gone wrong.
If play ever stops feeling like a choice, help is free and confidential: the National Gambling Helpline on 0808 8020 133, run by GamCare with BeGambleAware, and GamStop self-exclusion at gamstop.co.uk, which closes the door on every UK-licensed operator in one step.
Apple Pay casino questions, answered
Can I withdraw to Apple Pay?
Almost never. The wallet is a spending rail, so it works for deposits, while payouts are sent back to the debit card underneath at the one to three working day pace of card withdrawals. A few operators let a verified e-wallet handle exits in under 24 hours, but that wallet is a separate rail which must be set up and verified well before the withdrawal is requested.
Do wallet deposits count toward welcome offers?
Often, but not always. Because an Apple Pay transaction settles as an ordinary card payment, many offers accept it as a debit deposit. Some payment clauses exclude wallets by name, in which case the money still lands but no bonus credits. If the offer matters, fund the deposit by card instead; if it does not, the wallet keeps the balance free of turnover strings.
Is there a fee for using the wallet at a casino?
The model says no. Apple charges consumers nothing for the wallet, and cashiers at this end of the market typically charge nothing for wallet deposits, with debit card payouts usually free as well. What remains is the expected house edge on turnover and the waiting time on the payout leg, neither of which the payment rail adds to.
Why is my deposit instant but my withdrawal slow?
The token that makes deposits instant is a one-way credential, minted on the device for spending. Nothing equivalent exists for paying money back to a phone, so withdrawals travel to the underlying debit card, queue behind every other payout the operator is processing, and then clear through the banking system. One to three working days is the standard modelled window.
What deposit limits should I expect?
Typical minimums sit at £10, with some cashiers accepting £5, and upper limits of a few thousand pounds per transaction, subject to daily caps set by the operator. The debit card underneath carries its own issuer limits on top. Exact figures vary by account, so the cashier screen and the terms page, not a general article, remain the authority on any specific account.
Does a wallet deposit get around self-exclusion?
No. Self-exclusion at licensed operators blocks the person, not the payment method, and it applies whatever rail a deposit uses. A wallet transaction is a masked card payment under the same account checks, so it changes the packaging and never the coverage of the exclusion.
Is a wallet deposit safer than typing a card in?
On data security, arguably safer: the casino receives a token and a dynamic code rather than a card number, authentication happens on the device with Face ID or a passcode, and nothing card-shaped sits on the operator's servers. The risks worth managing are behavioural, chiefly the speed with which deposits can be made, rather than anything about the security of the rail itself.