non gamstop pay by phone casinos
Phone Billing Offshore: Why the Rail Rarely Travels
Carrier billing is a British rail with small caps and no payout leg; the model below times what takes its place when a cashier sits offshore.
The shortlist, before the detail
The board below carries this month's featured offers with their headline terms. The prose that follows models offers of this kind and never repeats those figures; the operator's own page is always the binding version.
Roulette King picks
Top roulette offers this month
The shortlist first, then the arithmetic. Four featured packages carry the headline terms below; the rest of the page models what offers of this kind usually cost and what a licence would have added.
Terms checked at the October 2026 review · 18+ · T&Cs apply. Offers move often: the operator’s own page is always the binding version.
- 1
 Night Luck82/100Casino welcome bonus 805% up to €6,400 + 280 FS
- MuchBetter · VISA · Apple Pay
- Crypto welcome 140% up to 1,600 USDT
- VIP pack 800% up to €14,500
Visit siteNight Luck18+ · T&Cs apply - 2
 EliteSpin80/100Welcome bonus €/£5,000 + 500 FS
- MuchBetter · NETELLER · MasterCard
- Lootboxes up to €/£20,000 or 500 FS
- BGaming festival: €80,000 prize pool
Visit siteEliteSpin18+ · T&Cs apply - 3
 Winbeast78/100Welcome pack €5,000 + 500 FS + €650 free bet
- MasterCard · Litecoin · MuchBetter
- Code FORTUNE: wheel on €40+ deposits
- Monday boost: 40% up to €300 (BOOST1)
Visit siteWinbeast18+ · T&Cs apply - 4
 Betportal75/100Welcome package 300% up to €/£1,000 + 150 FS
- Trustly · Bitcoin · Bank transfer
- 1st deposit: 150% up to €/£500 + 100 FS
- 2nd deposit: 100% up to €/£300 + 50 FS
Visit siteBetportal18+ · T&Cs apply
Placements on this board are paid, and the order is part of that arrangement. Featured brands hold no UK Gambling Commission licence, so GamStop, independent dispute resolution and segregated-funds rules do not reach them. Gambling can be addictive. Play responsibly. How we are paid.
A rail with small caps and no return leg
A phone-billed deposit is the quickest small transaction in British gambling. Pick an amount, reply to one text, and the money is sitting in the balance inside ten seconds, charged later to a pay-monthly bill or sliced off prepaid credit. The same speed has hard edges bolted on: minimums start at £10, the networks cap the rail at around £30 a day, and there is no return leg at all. Nothing pays back out through a phone number, so winnings always travel home by a different road. For a £10 flutter that design is ideal; for anything larger, the rail was never the plan.
That shape is a product of where the rail is built. Carrier billing for casinos in Britain runs through agreements with the mobile networks and the phone-paid services framework, which sets the caps, the confirmation flow and the paper trail. A cashier holding a UK licence can plug into it and offer phone billing as a first-class method, which is why the licensed lobbies all seem to have it. Run a search for non GamStop pay by phone casinos and you meet the wall one step later: a cashier operating from offshore rarely holds those network agreements, so the method simply never appears at the checkout, however strongly a review page implies otherwise.
The absence is quiet rather than dramatic. There is no hidden switch, and this page will not pretend to hold one. What exists instead is a set of substitute rails, each with its own clock, fees and minimums, and the honest job is to time them. That is what the rest of the page does, with every number labelled as a model and every assumption written out in full.
What takes its place at an offshore cashier
Stand at a cashier at this end of the market and the deposit menu narrows to three families. Cards lead: Visa and Mastercard debit, usually from £20, processed through acquiring chains that may sit nowhere near Britain. Vouchers come next, sold in fixed slices from £10 to £100 and redeemed with a PIN, which makes them the closest living relative of phone billing for anyone who likes paying in small, deliberate pieces. Crypto fills the rest of the window: USDT, Bitcoin and Ethereum in various wrappers, with minimums that typically start around the equivalent of £10 to £20.
The payout side is where the picture inverts. A card payment can be disputed or reversed after the event, which is exactly what an offshore-facing cashier does not want attached to a withdrawal, so the money leaves by other rails: crypto to an address you control, or an international bank transfer for larger sums. That one design choice explains most of what follows on this page. The rails that replace phone billing on the way in also decide how long the journey home takes, and the two clocks are not the same clock. It is also why minimum withdrawals sit higher than minimum deposits: the cheap rails only run one way.
E-wallets and instant banking turn up from time to time, but they are the garnish rather than the meal, and availability shifts with the acquiring deals of the month. The dependable trio is card, voucher and crypto, and the dependable payout rails narrow further still, which is why the chart in the next section keeps itself to four bars and no more.
The payout clock, rail by rail
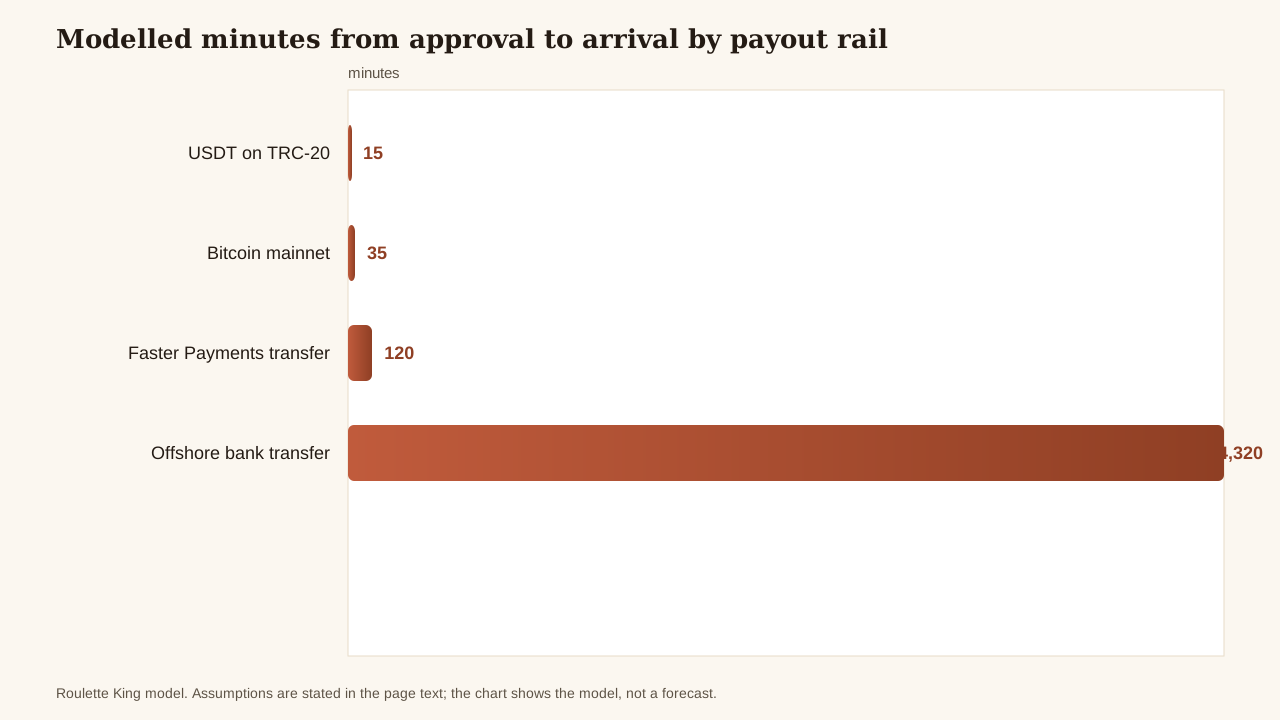
The chart below times the four rails that do the real work once a phone is out of the picture. Read it as a model rather than a stopwatch: every bar is the midpoint of a stated window, the clock starts after approval rather than at the withdraw button, and the assumptions sit in the text and the table underneath. Even so the shape is hard to miss. USDT on TRC-20 tops the chart at fifteen minutes. Bitcoin mainnet needs about 35. A Faster Payments transfer, where a cashier clears through a UK rail at all, lands in around 120 minutes, two hours end to end. An offshore bank transfer stretches out to 4,320 minutes, which is three days, and the slowest bar is 288 times the fastest.
| Payout rail | Modelled minutes, approval to arrival | Modelled minimum | Assumptions in the model |
|---|---|---|---|
| USDT on TRC-20 | 15 | £10 equivalent | Midpoint of a 10 to 20 minute window; one network confirmation; auto approval under the cashier's threshold |
| Bitcoin mainnet | 35 | £25 equivalent | Midpoint of 20 to 50 minutes; one confirmation at a next-block fee |
| Faster Payments transfer | 120 | £50 | Midpoint of 60 to 180 minutes; applies only where the cashier clears through a UK rail; weekday hours |
| Offshore bank transfer | 4,320 | £100 | Midpoint of a two to four day window, taken as 72 hours; correspondent hops and manual release |
Three assumptions do the heavy lifting. First, the clock starts at approval, meaning identity checks are already cleared; a fresh account waiting on documents adds time no chart can carry. Second, the crypto bars assume a single network confirmation, which is the fastest honest reading; a cashier that asks for two or three confirmations doubles the wait on paper. Third, the Faster Payments row is the optimistic one, because it exists only where a cashier maintains a UK clearing route, and that is the exception at this end of the market rather than the rule. Take the row away and the realistic choice is a quarter of an hour on a cheap chain, about half an hour on Bitcoin, or a three-day wait on a wire.
What a match bonus actually costs
Headline matches are the currency of this part of the market, so the model prices one. Assumptions come first: a £50 deposit with a 100% match, wagering set at forty times the bonus, because forty times is what this part of the market typically asks; slots contributing in full; and a modelled 96% return on the games. No name appears here because the arithmetic belongs to the structure, not to any single lobby. The required turnover is 40 × £50, which is £2,000 of stakes before a penny of the bonus unlocks.
At a 4% house edge, the expected cost of that turnover is £2,000 × 0.04, or £80. The bonus itself was worth £50, so the expected net lands at minus £30. That is the effective price of the promotion in the model: not an engine of profit, a longer session with a fee attached. The calculator below reworks the same arithmetic at whatever figures you feed it, and the shape rarely changes.
Effective bonus cost calculator
Deposit, match and multiple turned into credited money, turnover and a modelled cost.
Model illustration with stated inputs; the terms of a specific offer always override a model.
Time carries a price too. At £2 a spin, clearing £2,000 of turnover takes 1,000 spins, and at eight seconds a spin that is 8,000 seconds, a little over two hours of continuous play. Spread across an evening it shrinks, but the pattern holds: the bigger the multiple, the longer the treadmill, and the more swings of variance get a chance to bite before anything clears.
Small stakes and the nearest cousins
Part of phone billing's appeal is the tenner habit: small, capped, deliberate. Two substitutes keep most of that shape. Prepaid vouchers come closest, bought in fixed slices from £10 to £100 with a card or with cash, then redeemed as a PIN at the cashier; there is no bill at the end of the month and no card statement line to explain to anyone. A voucher also adds a small pause between wanting to deposit and completing it, which the phone rail achieves with its text confirmation. Low-value card deposits do the same job with less ceremony, though minimums of £20 are common at offshore-facing cashiers, double the British phone rail's floor.
One honest caution belongs here. Small-slice rails make spend feel lighter than it is: four £10 vouchers read as pocket money, while a £40 statement line reads as a decision. The caps that make carrier billing safe by design, £10 in and £30 a day, do not travel with the substitutes. Voucher ceilings vary by seller, and crypto minimums are set by network economics rather than by restraint, so the discipline the phone rail imposed has to come from the player instead.
If the tenner habit is the point rather than the means, the licensed rows in the comparison table further down the page are the only place the genuine rail still runs. Everything offshore is an imitation of it, and the imitation has different edges in every direction.
Limits, fees and conversion drag
The rails that replace phone billing carry costs the phone never showed. Crypto brings network fees that swing with congestion: a TRC-20 transfer costs pennies, while a Bitcoin fee can take a noticeable bite from a small withdrawal. Dollar-pegged stablecoins add conversion drag on the way out, because pounds to dollars at the cashier and dollars back to pounds at an exchange typically shave one to two per cent each way in the model.
Withdrawal limits stack on top of the fees. At this end of the market, weekly or monthly ceilings in the low thousands of pounds equivalent are common, larger sums are released in slices, and manual review above a threshold is standard practice. Where a ceiling exists, the model assumes it, and a three-day wire paid in slices can stretch past a week in practice. None of these figures is tied to a named brand on this page; they describe the shape of the market, and the model treats them as ranges rather than promises.
Cards complicate the return journey further. Some offshore-facing cashiers cannot push funds back to the card that funded the account at all, which pushes every payout onto crypto or bank rails regardless of how the deposit arrived. The practical read is simple: the method chosen on the way in sets the fees, the minimums and the clock on the way out, so choose it with the return trip in mind.
Cashiers compared on paper
The comparison table puts the market on a single page: where each cashier sits, what it is known for, and what a British regulator's rulebook adds or withholds. Known-for is reputation drawn from public positioning rather than a measurement, and nothing in the table is an endorsement of anything. It exists so the trade-offs sit side by side instead of scattered across separate paragraphs.
| Casino | Licence | Market focus | What it is known for | UK protections |
|---|---|---|---|---|
| Goldenbet | No UK licence | Offshore-facing casino | A cashier built around card and voucher deposits | None of the UK protections |
| Rolletto | No UK licence | Offshore-facing brand | Big-stake table play with crypto on the payout side | None of the UK protections |
| Donbet | No UK licence | Offshore-facing casino | A cashier that leans toward crypto | None of the UK protections |
| Kinghills | No UK licence | Offshore-facing casino | Eye-catching headline promotions | None of the UK protections |
| JackpotCity | No UK licence | Offshore-facing brand | A long-established lobby with card deposits | None of the UK protections |
| Gamdom | No UK licence | Crypto-first casino | Play that starts the moment crypto lands | None of the UK protections |
| MrQ | UKGC licensed | Mobile-led brand | Carrier billing treated as a main deposit method | GamStop, ADR, segregated funds |
| Pub Casino | UKGC licensed | UK brand | A plain, quick cashier that takes phone billing | GamStop, ADR, segregated funds |
| Ladbrokes | UKGC licensed | High-street brand | Card-led deposits with a mobile path alongside | GamStop, ADR, segregated funds |
| Coral | UKGC licensed | Mainstream brand | Cards set as the default, with a mobile route beside them | GamStop, ADR, segregated funds |
| Sun Bingo | UKGC licensed | Tabloid-partnered bingo | Little-and-often mobile deposits at bingo stakes | GamStop, ADR, segregated funds |
The licence column splits the table cleanly, and most of the rest follows from it. Where the licence reads UKGC, the final column fills up: GamStop coverage, an independent adjudicator for disputes, customer funds kept apart from the company's own. Where it reads no UK licence, that column stays empty by construction, whatever the rest of the row advertises, because those protections attach to the licence rather than to the cashier. The market focus column is a fair sketch of the cashier you will actually meet: card and voucher menus where the focus is offshore-facing, crypto as the main event where the focus is crypto-first, and carrier billing kept as a first-class deposit rail only among the licensed names. Read the final column as the price of admission for the first three.
What the licence buys you
A UK operating licence buys four things that matter at exactly the moment things go wrong. GamStop coverage comes first: enrol once at gamstop.co.uk and every licensed operator must close the door, which is why the scheme remains the strongest single tool a British gambler holds. Second, independent dispute resolution, so a stalled disagreement with an operator can go to an approved adjudicator without a legal bill. Third, segregated customer funds, which keep balances apart from the company's own money. Fourth, a regulator with the power to act on complaints, from fines to suspension to removal of the licence altogether.
Offers at cashiers without a UK licence carry none of that. Not less of it, none of it: no scheme enrolment, no adjudicator, no segregation of funds, no regulator to write to. That is the honest description of the market this page models, and it is the reason the payout clocks and the bonus arithmetic matter more here than they would at a licensed cashier, where the safety net catches what the fine print misses. Nothing here is a route around self-exclusion, and none is meant to be; a decision to exclude is a standing one, and it deserves to be treated that way.
If gambling has stopped feeling like a choice, the National Gambling Helpline on 0808 8020 133, run by GamCare with BeGambleAware, is open every day of the year; GamStop self-exclusion at gamstop.co.uk covers the licensed British market in a single enrolment.
Pay by phone at non GamStop casinos: questions answered
Can I pay by phone bill at a casino without a UK licence?
Rarely. Carrier billing in Britain runs through agreements with the mobile networks and the phone-paid services framework, and offshore-facing cashiers almost never hold those agreements. The practical substitutes are prepaid vouchers bought with a card or cash, or a small card deposit. Treat any cashier claiming direct phone-bill deposits at this end of the market as a claim to verify before you move a penny.
How fast are crypto payouts in the model?
The model puts USDT on TRC-20 at fifteen minutes from approval to arrival and Bitcoin mainnet at thirty five, both assuming one network confirmation and an auto approval under the cashier's threshold. The clock starts after checks clear, not when you press withdraw. A pending document request can add hours or days that no chart can predict.
What does a forty times wagering rule cost in pounds?
Work a £50 bonus at forty times: £2,000 of required stakes. At a modelled 96% return, four per cent of that turnover, £80, leaks back to the house in expectation. Set against the £50 bonus, the arithmetic lands at minus £30. The bonus is not free money; it is a longer session with a price tag attached.
Why is there a ten pound floor on phone deposits?
Carrier billing carries fixed processing costs between the network, the aggregator and the merchant, so a £1 deposit would lose money on every leg. A £10 minimum and a £30 daily cap keep the rail viable and keep impulse spending contained. Vouchers mirror the habit with fixed slices, commonly starting at a tenner.
Is Boku the same thing as pay by phone?
Boku is one of several aggregators that sit between a merchant and the mobile networks, rather than the rail itself. On a British cashier the experience feels identical: choose the amount, confirm by text, watch it land on the bill or the prepaid balance. Offshore, the agreements that make that flow possible are usually absent.
What slows a payout down in the model?
Three stages stack. Approval, which the model assumes is done and covers identity checks already cleared. Rail time, from about one network confirmation on a cheap chain to several correspondent hops on a bank wire. And minimums: a withdrawal below the cashier's threshold simply will not move, so small balances wait until they grow.
Does a phone-billed deposit appear on a credit file?
No. Carrier billing is not credit in the lending sense; on a contract the charge simply joins the monthly bill, and on prepaid it comes off the balance immediately. It does not involve a credit check and does not appear as borrowing. What does appear is the charge on the bill itself, which is why the small caps matter.
Do I need a crypto wallet before an offshore cashier will deal with me?
For withdrawals, usually yes, because many offshore-facing cashiers pay crypto by default and hold card rails for deposits only. A wallet is an address you control, plus a small amount of the chain's native coin to cover network fees. Exchanges can simplify the first transfer, though they add their own checks and fees to the journey.