paypal casino
Paypal casino
PayPal sits between cards and e-wallets on speed and above both on familiarity; the model below prices the rail end to end.
The shortlist, before the detail
The board below carries this month's featured offers with their headline terms. The prose that follows models offers of this kind and never repeats those figures; the operator's own page is always the binding version.
Roulette King picks
Top roulette offers this month
The shortlist first, then the arithmetic. Four featured packages carry the headline terms below; the rest of the page models what offers of this kind usually cost and what a licence would have added.
Terms checked at the October 2026 review · 18+ · T&Cs apply. Offers move often: the operator’s own page is always the binding version.
- 1
 Night Luck82/100Casino welcome bonus 805% up to €6,400 + 280 FS
- MuchBetter · VISA · Apple Pay
- Crypto welcome 140% up to 1,600 USDT
- VIP pack 800% up to €14,500
Visit siteNight Luck18+ · T&Cs apply - 2
 EliteSpin80/100Welcome bonus €/£5,000 + 500 FS
- MuchBetter · NETELLER · MasterCard
- Lootboxes up to €/£20,000 or 500 FS
- BGaming festival: €80,000 prize pool
Visit siteEliteSpin18+ · T&Cs apply - 3
 Winbeast78/100Welcome pack €5,000 + 500 FS + €650 free bet
- MasterCard · Litecoin · MuchBetter
- Code FORTUNE: wheel on €40+ deposits
- Monday boost: 40% up to €300 (BOOST1)
Visit siteWinbeast18+ · T&Cs apply - 4
 Betportal75/100Welcome package 300% up to €/£1,000 + 150 FS
- Trustly · Bitcoin · Bank transfer
- 1st deposit: 150% up to €/£500 + 100 FS
- 2nd deposit: 100% up to €/£300 + 50 FS
Visit siteBetportal18+ · T&Cs apply
Placements on this board are paid, and the order is part of that arrangement. Featured brands hold no UK Gambling Commission licence, so GamStop, independent dispute resolution and segregated-funds rules do not reach them. Gambling can be addictive. Play responsibly. How we are paid.
How PayPal fits into a casino cashier
PayPal occupies a particular place in a casino cashier: it is a wallet that stands between the player's funding sources and the operator, so the cashier talks to the wallet rather than to the bank or card behind it. A deposit therefore looks nothing like a card payment from the inside. Instead of typing a sixteen-digit number, the player confirms the amount inside PayPal, either through a redirect or an embedded checkout, and the operator receives a tokenised confirmation without ever seeing the underlying details. That separation is the quiet reason many players prefer the rail, and it is why a PayPal casino feels familiar from the first deposit: the mechanics are the ones shoppers have used for two decades.
Behind the wallet sit the usual funding sources: a linked debit card, a linked bank account, or a standing balance from earlier receipts. Which of those covers a deposit is a matter for PayPal and the player, not the operator, and that is one of several ways the wallet's rules differ from a card's. The cashier sees a cleared payment rather than an authorisation awaiting settlement, so the balance updates the moment approval lands and there is no pending stage to watch. Minimums at GB-licensed operators typically start at £10, in line with the card minimums that dominate the market, and playing in pounds keeps the wallet's currency-conversion charges out of the picture entirely.
The differences run deeper than checkout mechanics. PayPal operates its own merchant approval regime for gambling, separate from the card schemes, and it admits operators only where they hold a licence the wallet company recognises and accepts. Gambling transactions are coded as such, both sides keep their own records, and disputes travel through PayPal's resolution centre rather than the card chargeback process. Buyer protection, which covers undelivered or misdescribed goods in ordinary shopping, does not stretch to gambling losses; the protection people actually get here is architectural, meaning a layer between bank details and merchant, plus app-based approval and a notification for every movement of money.
Direction matters too. A card deposit can, in principle, be pulled back through scheme processes, which is exactly why card withdrawals travel through a tangle of scheme rules and settlement cycles. The wallet does not work that way: money that arrives as a deposit sits in the balance, money that leaves as a payout returns to the same wallet, and the rail is identical in both directions. Operators value that symmetry for its audit clarity. Players value it because a payout has one obvious destination, and the practical consequence shows up at cash-out, where the payouts section later on this page prices the journey end to end.
Familiarity does the rest of the work. The wallet predates most casino cashiers, its app already sits on many home screens, and the habit of checking it is decades old. None of that changes the mathematics of any game, and none of it makes an offer more generous; it simply removes friction at the exact point where friction is most felt, the moment money moves. A few habits of account hygiene matter more with this rail than with cards: keep the wallet verified with current details, keep the name on it matching the name on the casino account, and expect the operator's checks to read the wallet as a source of funds exactly as they would read a bank statement.
Deposit limits deserve a note in the wallet's favour. Operators ask players to set limits at account level, and the wallet does nothing to interfere with them, but it does make the act of depositing quicker, which is precisely why the limits should be set before the rail is used rather than after. A limit chosen calmly at signup does its work invisibly; the same limit chosen mid-session competes with the moment's momentum. Nothing here is unique to the wallet, but a faster cashier raises the stakes of the habits around it, and the habits are the player's to set.
At the till itself the flow is short. The player picks the wallet from the cashier's list, the checkout opens, the amount is confirmed in pounds, and the app asks for approval; a thumbprint on a phone covers most deposits now. Receipts arrive in the wallet's usual style, the transaction files itself in the account history beside every other payment it has ever made, and the casino balance updates at once. Nothing about the flow is gambling-specific, which is the point: the familiarity shoppers bring from other purchases is the same familiarity the cashier borrows.
Why, then, is the rail not universal? Approval costs an operator effort and ongoing scrutiny, and smaller or offshore-facing brands either cannot clear the bar or choose not to submit to it. The result is a market where the largest licensed names carry the wallet as standard while long-tail brands lean on cards and a handful of other e-wallets. The comparison table in the next section maps that split across familiar names, and the licence section explains why the split works as a useful signal rather than a marketing accident.
The speed model: four rails against the clock
Every model owes its assumptions an airing before the numbers can mean anything. This one reflects October 2026 practice at GB-licensed operators, and the windows are typical observations of how cashiers behave in ordinary circumstances, not promises; an individual cashier can run slower on a given day, and verification can hold any payout regardless of rail. Fees are modelled as none, because licensed operators do not typically charge for deposits and generally return withdrawals by wallet, card and bank transfer without a cashier fee. Where a wallet company charges for its own onward transfers, the note is made here rather than buried.
Four rails make up the model: the wallet this page is built around, the Visa debit card that remains the market's baseline, the bank transfer that persists alongside Faster Payments, and the prepaid voucher that behaves unlike anything else at cash-out.
| Rail | Model fee | Deposit speed | Payout speed | Notes |
|---|---|---|---|---|
| PayPal | none | instant | under 24 hours typical at licensed brands | same rail both ways |
| Visa debit | none | instant | 1 to 3 working days | card settlement |
| bank transfer | none | instant with Faster Payments | within 24 hours | account-name matching |
| paysafecard | none | instant | payouts need a bank rail | voucher by design |
Read the payout column first, because that is where the rails separate. Under 24 hours is the honest summary for a licensed PayPal casino, and in ordinary cases the wait runs shorter still, often a matter of hours once approval lands. Visa debit rides card settlement, and 1 to 3 working days is the candid window, stretched further by weekends and bank holidays since settlement counts in working days. Bank transfer surprises people in both directions: Faster Payments makes deposits instant despite the rail's old-fashioned reputation, and payouts return within 24 hours, with account-name matching doing quiet work against fraud at both ends.
The paysafecard row exists to make an asymmetry visible. A voucher is a deposit instrument by design, carrying money in one direction only, so payouts need a bank rail before they can land anywhere useful. Operators handle it by sending withdrawals to a verified bank account after the voucher has done its job at the till. The lesson generalises beyond one brand of prepaid card: a rail's deposit convenience says nothing about its cash-out behaviour, and the two directions have to be priced separately. That principle is what the model applies to the wallet, which is unusual in offering the same rail both ways and therefore scores well on both.
Different rails suit different players, and the model makes the trade-offs legible. A player who cashes out weekly and spends from the wallet will value the two-way speed above all; a player who banks winnings immediately may not notice the difference between hours and working days, since the wallet's onward transfer to a bank runs its own timetable anyway. A player who deposits with a voucher for budgeting reasons accepts the payout asymmetry knowingly. The point of a model is not to crown one rail but to show which costs each one charges, and where those costs land on a particular pattern of play.
A caveat belongs beside any speed table, however carefully it is built. Operator processing is only half the journey; identity checks, source-of-funds questions and the wallet's own transfer timetable all add time of their own. The windows here describe verified accounts in ordinary cases, and they are stated as observations precisely because no honest writer can promise a clock. Models earn their keep by being questioned, so a reader whose experience runs slower should check the usual culprits first: an unverified wallet, a bonus still clearing, or a withdrawal requested minutes after a deposit, which some cashiers hold for review. None of these make the windows wrong; they sit outside them.
Where the wallet sits across the market
The comparison below groups familiar names by market focus, because the same rail behaves differently inside a bingo-led brand than inside a bookmaker.
| Casino | Licence | Market focus | What it is known for | UK protections |
|---|---|---|---|---|
| Virgin Games | UKGC licensed | games-led brand | PayPal as a first-class cashier rail | Yes, full scheme |
| JackpotJoy | UKGC licensed | games brand | PayPal deposits and payouts | Yes, full scheme |
| Heart Bingo | UKGC licensed | bingo-led brand | PayPal with small-stake play | Yes, full scheme |
| Sun Bingo | UKGC licensed | tabloid-partnered bingo | PayPal deposits beside cards | Yes, full scheme |
| MrQ | UKGC licensed | no-wagering pioneer | PayPal payouts among the fastest | Yes, full scheme |
| PlayOJO | UKGC licensed | no-wagering model | PayPal cash-outs without wagering attached | Yes, full scheme |
| 888 Casino | UKGC licensed | long-running standalone casino | PayPal with a long cashier history | Yes, full scheme |
| William Hill | UKGC licensed | high-street heritage | PayPal beside debit rails | Yes, full scheme |
| Betfred | UKGC licensed | bookmaker with a card-first cashier | PayPal for casino payouts | Yes, full scheme |
| Paddy Power | UKGC licensed | bookmaker | PayPal across the wallet | Yes, full scheme |
| BoyleSports | UKGC licensed | bookmaker | PayPal deposits | Yes, full scheme |
| PartyCasino | UKGC licensed | casino-first brand | PayPal with published bonus terms | Yes, full scheme |
| Gala Bingo | UKGC licensed | bingo-led brand | PayPal for room tickets | Yes, full scheme |
| Foxy Bingo | UKGC licensed | bingo-led brand | PayPal deposits on mobile | Yes, full scheme |
| Kinghills | No UK licence | offshore-facing casino | PayPal rare at this end of the market; e-wallets and crypto instead | None |
Virgin Games and MrQ make the sharpest pair for contrast. The former treats PayPal as a first-class cashier rail inside a games-led brand, with the wallet sitting beside cards as core furniture rather than an afterthought; the latter, a no-wagering pioneer, is known for PayPal payouts among the fastest precisely because there are fewer strings to unwind before money can leave. Both hold the same licence, and that shared footing is the point: market focus shapes a cashier far more than the presence of the wallet alone.
Grouping by market focus does real analytical work. Bingo-led brands such as Heart Bingo, Sun Bingo, Gala Bingo and Foxy Bingo built their cashiers around small-stake, high-frequency play, so their wallet flows lean toward modest deposits and mobile checkouts. Bookmakers such as William Hill, Betfred, Paddy Power and BoyleSports carry the wallet beside their debit rails, with the known-for lines recording deposits, payouts and everything between. Games brands and standalone casinos, from Virgin Games and JackpotJoy to 888 Casino and PartyCasino, treat the wallet as a mainstream option, which is the classic shape of a PayPal casino. MrQ and PlayOJO occupy a no-wagering corner where the rail matters differently, since a payout that lands without conditions attached is worth more than a larger figure that must be played through first.
The final row breaks the pattern deliberately. Kinghills appears with no UK licence and none of the protections the other names carry, and its known-for line says the quiet part aloud: PayPal is rare at this end of the market, with e-wallets and crypto instead. That absence is not a reviewer's verdict but a consequence of the wallet company's own approval rules, which keep gambling transactions inside licensed markets. A cashier offering the wallet is, for that reason alone, unlikely to be entirely outside regulation, while a cashier that cannot offer it deserves questions about why.
Treat the table as a map of cashier cultures rather than a ranking. Two brands with identical rails can feel different at the till because one runs a bonus-led model and the other does not, and the known-for column records behaviour rather than advertising. Where a cashier matters more than a lobby, the licence and protections columns deserve reading first; everything else is commentary resting on them.
Cash-outs: what a two-way rail changes
Most payment writing stops at the deposit, which is a shame, because the deposit is the easy direction for every rail in the model: instant, familiar, frictionless. The payout is where rails earn their reputations, since leaving money is harder than taking it. Settlement cycles, scheme rules, anti-fraud checks and operator processing all queue up between a cash-out request and money in hand, and the length of that queue is what separates a wallet from a card.
PayPal is a two-way rail in the fullest sense: the same account that carried the deposit receives the payout, and the operator routes money back to its origin by default. That routing has an administrative name, the closed loop, and it exists for anti-money-laundering reasons, but its practical effect is simplicity. No bank details need re-entering, no third-party wallet exists that only accepts deposits, and no card scheme sits in judgement on whether a withdrawal may ride its rails. Money returns where it came from, which keeps the audit trail clean for the operator and the journey short for the player.
The clock splits into two halves. The first belongs to the operator: the window between a cash-out request and its approval, during which identity, source-of-funds and wagering checks run. Licensed brands publish or imply their processing windows, and much of the market approves wallet payouts within a day, frequently within hours. The second half belongs to the rail: the transfer from operator to wallet, which for PayPal usually takes minutes to a couple of hours once approved. Added together, the two halves explain the under-24-hours figure in the model table, with many ordinary cases landing well inside it.
Then comes the wallet's own onward journey, which the model leaves unpriced because it sits outside the cashier. A PayPal balance can be spent online immediately, or transferred to a linked bank account, where standard transfers typically arrive within a working day. That extra hop is optional, and players who treat the wallet as a spending account skip it altogether. Measured against cards, where the equivalent window runs 1 to 3 working days, or against vouchers, which need a bank rail before payouts can land anywhere, the two-way rail's advantage compounds with every cash-out.
Friction at this end is mostly self-inflicted, which is the good news. A wallet whose name does not match the casino account invites questions; an unverified wallet invites holds; a request submitted before wagering conditions clear invites rejection and a slower second attempt. None of these are faults of the rail, but the two-way design exposes them quickly, because the payout has a single obvious destination and any mismatch announces itself on arrival. Verified, matching, tidy accounts are the ones for which the model's windows hold as written.
Expectations are part of the machinery too. A payout requested late on a Friday evening may sit until Monday at operators whose processing runs on working days, through no fault of the rail; the transfer afterwards remains quick, but the approval half of the clock waited for the office. Players who cash out midweek tend to see the model's windows at their best. None of this is disclosed as a promise anywhere worth trusting, which is why this page prices windows as observations and keeps the word typical doing honest work.
The figure below compresses the model's headline contrast into one picture: two clocks starting at the same moment, diverging at the transfer stage.
Read the figure as a comparison of halves rather than a stopwatch. Both bars begin at approval, because the operator's processing window is a shared cost whatever the rail; they part company in the transfer stage, where the wallet clears in hours while the card waits on settlement. For anyone cashing out ahead of a weekend, the difference can amount to a bank holiday's worth of waiting, and small, repeated advantages of that kind are what decide which rail a household actually comes to rely on.
Bonus eligibility on PayPal deposits
Payment method and bonus eligibility intersect more often than players expect, and the intersection is governed entirely by an operator's promotional terms rather than by anything inherent in the wallet. Some offers list the payment methods that do not qualify; others exclude whole families of wallets; a few welcome every rail equally. The exclusions exist for a plain commercial reason: fast wallets make it easy to move money in, extract a bonus and move out again, so operators with bonus-led models have historically restricted the quickest rails to slow that abuse down.
PayPal's position in that history is unusual. Skrill and Neteller were the wallets most commonly excluded from welcome offers, and the exclusion habit formed around them years before PayPal arrived widely in gambling cashiers. Carrying a consumer brand with mainstream expectations, the wallet was excluded less often than its rivals, but it is not immune: specific offers at specific operators do leave it out, and the only reliable source is the terms attached to the offer in question. The habit worth forming is mechanical, meaning the eligible-methods line gets read before the deposit, because the difference between rails can be the difference between an offer and an ordinary deposit.
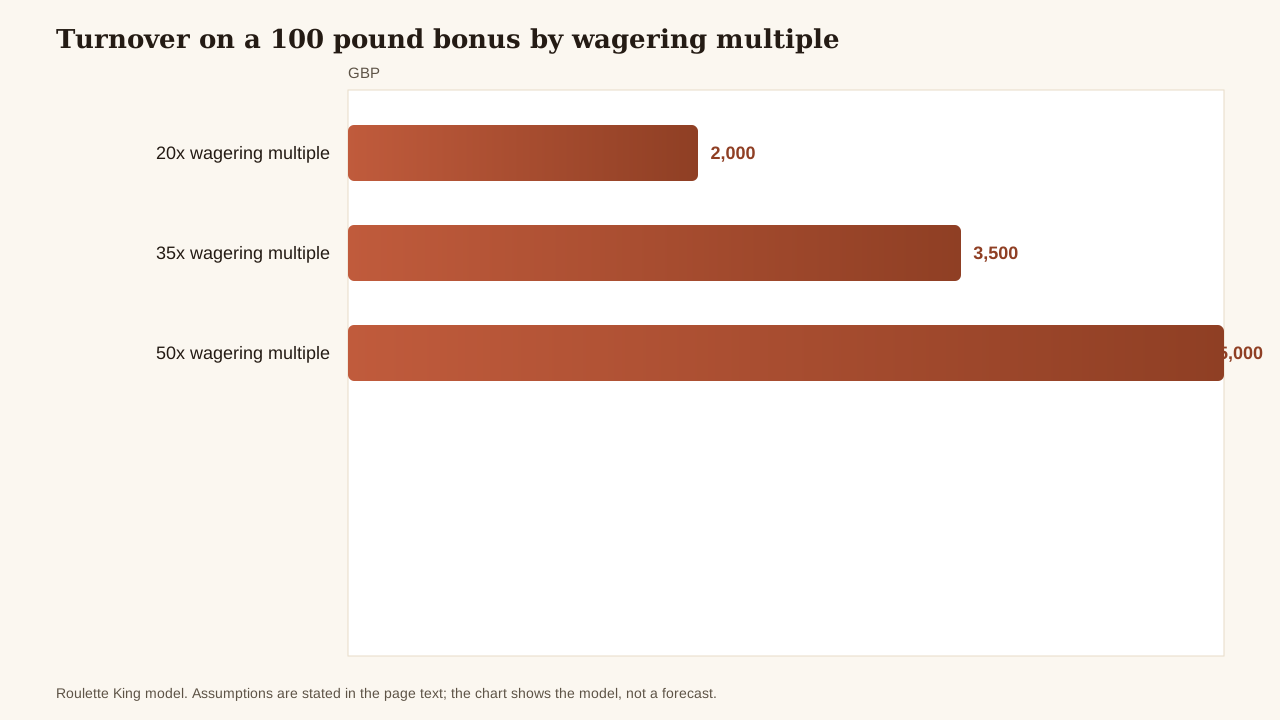
Reading terms is a skill of narrow attention, and three lines carry most of the weight. The first is the eligible payment methods, which settles whether the rail qualifies at all. The second is the wagering multiplier and its base, because 30x on the bonus is a different animal from 30x on deposit plus bonus. The third is game weighting, which decides how much of each stake counts toward the requirement; slots typically count in full while table games often count for little or nothing, and a multiplier that looks modest on paper can grow enormous once weighting is applied.
A worked example keeps the arithmetic honest. Assume a £20 bonus with a 30x multiplier applied to the bonus alone: qualifying play comes to £600 before a withdrawal unlocks, since 30 multiplied by £20 gives £600. Assume instead that the same 30x applies to a £20 deposit and its £20 bonus together: the base doubles to £40 and qualifying play rises to £1,200, twice the work for the same headline multiplier, purely because of where the multiplier attaches. These are illustrations with their assumptions stated in full, and the calculator exists to replace them with the reader's own figures.
Run the multiplier against your own deposit and offer terms with the wagering model below.
Wagering calculator
Turnover before withdrawal, modelled from the bonus and the multiple the terms set.
Model illustration with stated inputs; the terms of a specific offer always override a model.
Treat the output as a budget for attention rather than a target for play. It states the size of the qualifying task in pounds of stakes, which is the number that decides whether an offer suits a given bankroll and temperament. Where the task outweighs the entertainment an offer would otherwise provide, the sensible move is to deposit without taking the bonus, keep any payout untethered, and let the two-way rail do what it does. On that point the no-wagering corner of the market earns its reputation by subtraction: nothing to clear means nothing to argue about at cash-out.
What a licence buys you
Everything else on this page is convenience; the licence is the part that carries weight. A Gambling Commission licence, held by every operator marked UKGC licensed in the comparison table, buys a set of protections that no offshore-facing brand replicates, and they deserve spelling out in full rather than a wave of the hand.
The first protection is GamStop, the national self-exclusion scheme covering every GB-licensed operator. One registration at gamstop.co.uk excludes a person from all of them at once, for a chosen term of six months, one year or five years, and operators are required to act on it. No unlicensed brand participates, so exclusion at that end of the market depends on each operator's goodwill rather than on a system built for the purpose.
The second is independent dispute resolution. When a complaint between player and operator stalls, a licensed operator must refer it to an approved alternative dispute resolution service, which examines the evidence and issues a decision the operator is expected to honour. Unlicensed brands offer no equivalent; a complaint travels nowhere except back to the operator's own inbox, where it competes with the operator's own interest.
The third is the treatment of player balances. Licence conditions require customer funds to be held separately from business funds, so a company's insolvency does not take players' money with it. The balance showing in a cashier at a licensed operator is protected money in a way a balance elsewhere simply is not, and that difference never matters until the day it matters enormously.
The fourth is a regulator who acts on complaints. The Gambling Commission takes reports, investigates, and holds real powers, among them fines, conditions, suspensions and revocations. Its rules also reach into fairness and safety: games must run on certified random number generators, advertising must sit within strict codes, and affordability and source-of-funds checks must appear at defined points. The existence of those powers explains why licensed operators tend to settle complaints they might otherwise ignore, and why their published terms tend to mean what they say.
Offers without a UK licence carry none of this. No GamStop access, no independent adjudication, no segregated funds, no regulator who acts. Terms are enforced, where they are enforced at all, by the operator's discretion, and a player's recourse runs out at a customer service address. The comparison table's final row exists to make that contrast concrete: the licence column and the protections column move together, and where one reads no, so does the other.
The wallet fits into this picture more directly than most payment facts. PayPal's merchant approval keeps gambling transactions inside licensed markets, so the rail rarely appears at offshore-facing brands, and its presence works as a weak but genuine signal of regulation. The known-for line recorded for that end of the market, e-wallets and crypto instead, is the practical consequence of those approval rules rather than anyone's editorial preference.
Two resources belong on every page of this kind because they are the ones that matter when the subject stops being about payments. GamStop's registration site is gamstop.co.uk, and it is free to use. The National Gambling Helpline is on 0808 8020 133, run by GamCare with BeGambleAware, open every day of the year to anyone affected by gambling, including family and friends. Neither depends on where an account is held, and both are a phone call or a visit away.
None of this is a comment on any single cashier's honesty; it is a comment on what exists when something goes wrong. Licensed operators fail too, and complaints still need making, but the framework around them means a complaint has somewhere to go and someone with power at the end of it. That is the whole difference a licence makes, and it is why the licence column sits in plain sight on this page rather than in the small print.
PayPal limits and account controls: setting the ceiling before the deposit
A deposit limit lives at the casino account, not inside the wallet, and that distinction shapes how the two systems interact. When a player sets a limit of £100 a week at a licensed operator, the cashier enforces it against deposits, counting every amount that crosses the till whichever rail carries it. The wallet's top-up sits one layer below: moving money from a linked debit card into the PayPal balance is a wallet transaction, invisible to the casino, and it never counts towards the operator's figure. The consequence is easy to state and easy to miss. Topping up a wallet with £200 does not deposit £200 anywhere; it only loads the pipe, and the operator's counter moves later, by exactly the amount confirmed at the cashier.
The interaction runs the other way too, and it is where care pays. Because a top-up is invisible to the casino, a player who funds the wallet generously and then deposits in small amounts can lose sight of the total movement of money across a month: the operator's history shows £40 here and £30 there, while the wallet's history shows a single £200 top-up that dwarfed them both. Reading the two statements side by side is the habit that closes the gap. A second wrinkle concerns funding sources: where a wallet draws on a card, the issuer sees a payment to PayPal rather than to the casino, which some players find tidier on a bank statement. The operator's affordability reviews still read the deposits clearly, because they examine the casino account rather than the card feed, but the wider paper trail changes shape, and knowing that beforehand is worth more than discovering it later.
Self-imposed limits announce themselves at the cashier in plain terms. Once a daily, weekly or monthly ceiling is set, the deposit page typically shows the allowance remaining in the current period, and an attempt above it is refused before the wallet checkout ever opens: the player chooses an amount, the cashier checks it against the running total, and the refusal arrives with a message naming the limit and the period it covers. The wallet never sees the rejected amount, because the operator's check happens first. Lowering a limit takes effect immediately, which is the direction the design encourages; raising one triggers a cooling-off period, commonly twenty-four hours, so the decision has to survive a wait. Loss limits and session reminders often sit beside the deposit counter, and all of these controls live at account level, blind to which rail carried the money. For a wallet user the practical effect is simple: no method of payment softens a ceiling once it is set.
Keeping a single funded wallet earns its keep at the payout stage. The closed loop sends money back to its source by default, so a player who deposits from one wallet receives payouts into that same wallet without re-entering anything. Spread deposits across two wallets and a card, and the operator must route refunds along their original paths, which is slower to approve and fussier to reconcile; verification questions also multiply, because each destination needs its own checks and its own name match. One wallet, funded and verified, keeps the audit trail straight: every deposit and every payout files into a single account history, the operator's reviews read one story rather than three, and the onward journey to a bank account, if wanted, is a single transfer with a single timetable. It is a small discipline that removes whole categories of delay.
A worked example fixes the ideas, with every assumption stated. Suppose a player holds a £120 monthly deposit limit at a licensed operator, a fresh wallet and a linked debit card behind it. On the 1st the player tops the wallet up with £150; this is a wallet transaction and does not touch the casino's counter. Deposits follow at the cashier: £40 on the 3rd, £30 on the 10th and £50 on the 17th, taking the monthly total to exactly £120. On the 20th a £65 payout is approved and returns to the wallet, the only source used, so the routing is automatic. The balance then reads £95, because £150 minus £120 of deposits plus £65 of payout leaves £95. On the 24th the player attempts a further £20 deposit and the cashier refuses it, since the monthly limit is spent; the wallet's healthy balance makes no difference to that refusal. The player moves the £95 to a linked bank account by standard transfer, assumed here to arrive within a working day at no charge. Every figure is illustrative: limit £120 a month, top-up £150, deposits £120 in total, payout £65, closing balance £95, transfer free and next working day. The lesson sits in the refusal at the end: the limit counts what crosses the cashier, not what sits in the wallet.
A closing word belongs to the habit rather than the mechanics. A fast wallet makes limits more valuable, not less, because the friction that once slowed a deposit has gone; the ceiling is the friction now, and it works only if it is set while calm. Licensed operators invite players to choose limits at signup, the wallet does nothing to interfere with them, and the cooling-off rule on increases exists precisely for the moment when enthusiasm argues for a bigger number. Set the counter first, keep one wallet tidy behind it, and the rail's speed becomes a convenience rather than an accelerant.
Frequently asked questions
Is PayPal available at GB-licensed casinos?
Yes, broadly. An established licensed PayPal casino almost always carries the wallet beside its debit rails, and every operator marked UKGC licensed in the comparison table does; the list spans games brands, bingo-led brands and bookmakers, which is a fair cross-section of the market. Availability rests on a two-sided approval: the operator must hold a licence the wallet company accepts, and it must pass the wallet's merchant checks. A few smaller licensed brands lack the rail for commercial reasons, so absence from a cashier is possible even under a licence, while presence at an offshore-facing brand is rare. The cashier's deposit page is the only list that counts, so check it before assuming anything.
How fast do PayPal payouts arrive?
Under 24 hours is the typical window at licensed brands, counted from the moment the cashier approves the payout to the moment the balance shows in the wallet. In ordinary cases with verified accounts, approval itself often arrives within hours and the transfer afterwards takes minutes to a couple of hours, so many payouts land the same day. The model's windows are observations rather than promises, and three things stretch them: identity or source-of-funds checks, first withdrawals on a fresh account, and weekend requests, since some operators process approvals only on working days. The card baseline for the same journey is 1 to 3 working days, which is the comparison the payouts section prices in detail.
Do PayPal deposits lose bonus eligibility?
Sometimes, and never by accident. Eligibility is governed by the terms attached to each offer, and those terms name the payment methods that qualify. Historically the exclusions clustered around Skrill and Neteller, the wallets most associated with bonus abuse; PayPal is excluded less often, but specific offers do leave it out, particularly at operators with bonus-led models. The habit worth forming is mechanical: find the eligible-methods line before depositing and read the wagering multiplier beside it. If the wallet is excluded, the deposit still works, but the offer will not pay out on it, which is a disappointing way to discover what the terms said.
What fees apply to PayPal at casino cashiers?
At the cashier, typically none. Licensed operators do not generally charge for deposits by any rail, and withdrawals to the wallet are usually free, which is what the model assumes when its fee column reads none. The wallet's own charges live outside the cashier: moving a balance to a linked bank account can carry a charge for an instant transfer, while standard transfers usually arrive within a working day at no cost. Currency conversion is the other place fees appear, and it is avoidable by keeping the account in pounds, which every GB-licensed cashier transacts in. The rail is cheap, but the wallet's onward terms deserve a glance in its own help pages.
Does PayPal work at offshore-facing brands?
Rarely, and the terms are weaker when anything similar is on offer. PayPal's merchant rules keep gambling transactions inside licensed, regulated markets, so offshore-facing brands seldom carry the wallet at all; the table's final row records exactly that, with e-wallets and crypto instead. This is not a judgement made by reviewers but a consequence of the wallet company's approval process, which is why the rail's presence reads as a signal of regulation. The deeper issue is that a brand without a UK licence also lacks GamStop, independent dispute resolution, segregated funds and a regulator who acts on complaints, so the cashier question and the protection question have the same answer at that end of the market.
How do PayPal limits compare with cards?
Broadly similar at licensed brands, with the wallet adding a layer of its own. Minimum deposits commonly start at £10 whichever rail is used, and the model's October 2026 observations put wallet and card minimums side by side at that level across much of the market. Maximums are set per operator rather than per rail, and affordability checks apply regardless of method. What PayPal adds is a wallet-side ceiling, since the balance and the funding sources behind it impose limits of their own, which occasionally matters for larger transactions. For everyday play the rails are interchangeable on limits; for unusually large movements, the wallet's own account terms are worth checking before the deposit rather than after.
Do deposits and withdrawals use the same rail?
Yes for PayPal, and that symmetry is the rail's defining trait. The same wallet that carried the deposit receives the payout, by default and without re-entering details, which keeps the operator's anti-money-laundering checks straightforward and the player's journey short. Cards behave similarly where scheme rules allow a withdrawal to return to the original card, though settlement still takes 1 to 3 working days. Bank transfers return to a verified account, with account-name matching doing the checking. The exception is paysafecard, a deposit-only voucher by design, whose payouts need a bank rail to reach anywhere useful. Two-way rails are the norm at licensed brands precisely because the closed loop keeps the audit trail clean.
What does the licence gap mean in practice?
It means every protection on the licensed side of the table disappears at once. No UK licence means no GamStop access, so self-exclusion becomes a per-operator request rather than one registration covering the market. It means no independent dispute resolution, so a stalled complaint goes nowhere except back to the operator. It means no segregated funds, so a balance is only as safe as the company holding it. And it means no regulator who acts on complaints, which removes much of the incentive operators have to settle. The practical advice is short: keep play inside the licensed market, and if the subject turns from payments to harm, the National Gambling Helpline on 0808 8020 133, run by GamCare with BeGambleAware, is the right call.