google pay casino
Google Pay Casino: Android Cashier Behaviour Modelled
The wallet clears a deposit in seconds; the model below shows where the hours actually go when the winnings come back out.
The shortlist, before the detail
The board below carries this month's featured offers with their headline terms. The prose that follows models offers of this kind and never repeats those figures; the operator's own page is always the binding version.
Roulette King picks
Top roulette offers this month
The shortlist first, then the arithmetic. Four featured packages carry the headline terms below; the rest of the page models what offers of this kind usually cost and what a licence would have added.
Terms checked at the October 2026 review · 18+ · T&Cs apply. Offers move often: the operator’s own page is always the binding version.
- 1
 Night Luck82/100Casino welcome bonus 805% up to €6,400 + 280 FS
- MuchBetter · VISA · Apple Pay
- Crypto welcome 140% up to 1,600 USDT
- VIP pack 800% up to €14,500
Visit siteNight Luck18+ · T&Cs apply - 2
 EliteSpin80/100Welcome bonus €/£5,000 + 500 FS
- MuchBetter · NETELLER · MasterCard
- Lootboxes up to €/£20,000 or 500 FS
- BGaming festival: €80,000 prize pool
Visit siteEliteSpin18+ · T&Cs apply - 3
 Winbeast78/100Welcome pack €5,000 + 500 FS + €650 free bet
- MasterCard · Litecoin · MuchBetter
- Code FORTUNE: wheel on €40+ deposits
- Monday boost: 40% up to €300 (BOOST1)
Visit siteWinbeast18+ · T&Cs apply - 4
 Betportal75/100Welcome package 300% up to €/£1,000 + 150 FS
- Trustly · Bitcoin · Bank transfer
- 1st deposit: 150% up to €/£500 + 100 FS
- 2nd deposit: 100% up to €/£300 + 50 FS
Visit siteBetportal18+ · T&Cs apply
Placements on this board are paid, and the order is part of that arrangement. Featured brands hold no UK Gambling Commission licence, so GamStop, independent dispute resolution and segregated-funds rules do not reach them. Gambling can be addictive. Play responsibly. How we are paid.
What Google Pay does at a casino cashier
A deposit through Google Pay posts in seconds, and the speed is the whole pitch. The wallet pushes a tokenised stand-in for your debit card to the cashier, the cashier confirms the payment without ever seeing the card number, and the balance is ready to stake before the payment sheet closes. The model on this page prices that deposit leg at zero hours, then follows the money on the way out, where an average approval window of 6 hours and a debit card settlement priced at 48 hours absorb almost all of the waiting.
Under the bonnet, Google Pay replaces the card's primary account number with a device specific token, sometimes called a DPAN. The merchant captures that token, a cryptogram and a transaction reference, so a breach of the cashier's systems exposes far less than a typed card form would. For the customer the difference is mostly friction. There is no sixteen digit number to type, no CVV to read out, and one biometric or passcode confirmation covers the whole payment.
There is one platform boundary to know. Google Pay lives on Android, in apps and in the Chrome payment sheet on the mobile web, so the behaviour described here is Android behaviour by definition. On iPhone the equivalent rail is Apple Pay, and a Google Pay casino will usually run both sheets side by side rather than forcing a choice between devices.
The card behind the wallet sets the terms
Google Pay is a wrapper around an ordinary Visa or Mastercard debit card. The cashier's rulebook rarely writes about wallets at all; it writes about card payments, and the tokenised transaction presents as a card deposit. Everything that attaches to the card attaches to the payment: bonus eligibility, verification of the cardholder name, and the settlement path a payout eventually follows. The wallet changes the front end. It does not change the plumbing.
Since 14 April 2020, credit cards cannot fund gambling in Great Britain, so the card inside the wallet has to be a debit card for a licensed cashier to accept it. That single fact does a lot of quiet work. It means the deposit is treated as debit card spend by your bank, it means the affordability conversation with your bank is unchanged, and it means the terms you are agreeing to are the ones written for card deposits rather than for third party e-wallets.
Payout timing follows the card for the same reason. Very few cashiers push a withdrawal back through the wallet, because Google Pay's rails are built around authorising payments, not receiving them. The money therefore travels to the underlying debit card, and card settlement cycles apply, which is where the 48 hour figure in the model comes from.
The approval window, priced in hours
The approval window is the stretch between pressing withdraw and the cashier releasing the payment. The model takes 6 hours as its average, because that is broadly what this part of the market shows once routine queues, identity checks and payment-source reviews are weighed together. It is the one stage the wallet cannot touch: Google Pay authorises money going in, and it has no say over money coming out. Weekends, first-time withdrawals and larger sums all stretch the window past the average.
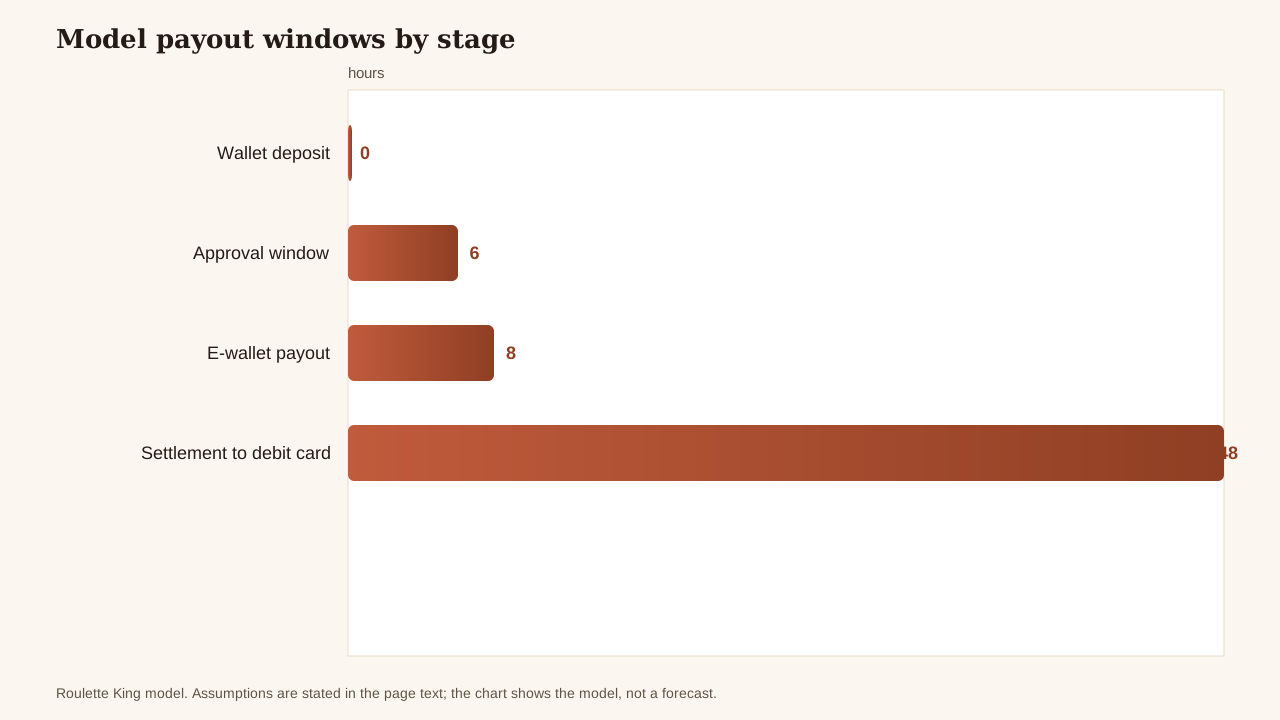
Read the chart left to right and the shape of the problem appears. The deposit bar sits at zero. Approval completes around hour 6. An e-wallet payout lands around hour 8, which is the 6 hour window plus a short transfer leg. A settlement to the underlying debit card lands at hour 48, the midpoint of the 24 to 72 hour band the model assumes for card payouts. The difference between hour 8 and hour 48 is the price of a card exit, measured in modelled hours.
Treat the 6 hour figure as a planning number rather than a clock. If a withdrawal is needed for a bill due Tuesday, the model suggests requesting it on Monday morning, not Monday evening, because the window does not compress for deadlines. First withdrawals and sums above a few hundred pounds are the two triggers most likely to add reviews to the queue.
The modelled journey, stage by stage
The table below compresses the same assumptions into one view. Each row is a stage, each figure is hours measured from the moment you request the withdrawal, and the assumption column states what the model is taking for granted. Nothing here is a promise about any individual cashier. It is a way of seeing which stage deserves your attention, and which stage you can actually influence.
| Stage | Modelled hours from request | What moves it | Assumption |
|---|---|---|---|
| Wallet deposit | 0 | Tokenised push through Google Pay, no card details typed | Instant by design, counted as zero |
| Approval and review window | 6 | Cashier queues, identity and payment-source checks | Averaged at 6 hours across this part of the market |
| E-wallet payout | 8 | Transfer out once approval clears | Assumes a 2 hour transfer leg after the 6 hour window |
| Settlement to debit card | 48 | Card scheme settlement cycles on the underlying card | Band of 24 to 72 hours, priced at the 48 hour midpoint |
Two conclusions fall out of the table. First, the only stage you control at deposit time is the zero hour one, so choosing a rail for the money going in says little about the money coming out. Second, if the cashier offers an e-wallet exit and you hold one, the model says that choice is worth roughly 40 hours, because it steps around card settlement entirely. The approval window stays in every route. It is the toll both roads pay.
Wagering maths with the assumptions in the open
Deposits are the fast part, so the calculator turns to the slow part instead. The model takes forty times the bonus as its wagering multiple, because that is what this part of the market typically asks. Feed it a deposit and a match rate and it returns the total stakes required. Worked by hand: a £20 deposit with a 100 percent match creates a £20 bonus, and 40 multiplied by £20 is £800 of wagering before a withdrawal can be requested.
Wagering calculator
Turnover before withdrawal, modelled from the bonus and the multiple the terms set.
Model illustration with stated inputs; the terms of a specific offer always override a model.
At £1 spins, £800 is 800 spins, and at a steady 300 spins an hour it is a little over two and a half hours of play. Halve the stake to 50p and the spins double to 1,600 while the requirement stays put, which is the quiet truth of wagering: the multiple prices time, not just money. Change the multiple to 30 times and the same £20 bonus costs £600, saving 200 spins of the modelled journey.
Weighting matters too. Most rulebooks count slot play at 100 percent and table games at 10 percent or less, so £100 staked on roulette might contribute £10 toward the requirement. The calculator assumes slot play at full weight. If a session mixes games, the effective hours stretch further than the headline figure suggests.
Why the underlying card decides bonus eligibility
Exclusion clauses in bonus terms are written by payment family. Named e-wallets such as Skrill and Neteller are the usual targets, because those wallets were historically the tool of choice for bonus abuse. A Google Pay transaction does not look like that to the cashier. It presents as a tokenised debit card payment, so it normally inherits the card's eligibility, and the deposit qualifies where a card deposit qualifies. At a typical Google Pay casino, the deposit menu may even label the button card, with the wallet sheet appearing after you pick an amount.
The exceptions worth reading for are three. Some terms exclude prepaid instruments, and a wallet sitting on a prepaid card can fall foul of that. Some offers attach to specific deposit minimums, which is a threshold question rather than a rail question. And some rulebooks require the withdrawal method to match the deposit method, which nudges the payout back toward the card behind the wallet and reinforces the 48 hour settlement assumption.
Verification is the last card-shaped hook. The name on the account has to match the cardholder, and that check tends to surface at payout time rather than at deposit time, which is one of the reasons the approval window exists in the model at all. A wallet does not remove the requirement. It simply delays the point where it bites.
Deposit limits, fees and the small print
On costs, the picture is unusually clean. Google charges nothing for the service, licensed cashiers do not add a handling fee to deposits, and the underlying debit card records an ordinary purchase rather than a cash advance. The expense in this market hides in the wagering multiple, not on the rail, which is why the calculator is pointed at the bonus rather than at the deposit.
Limits are layered. The cashier sets its own minimum, commonly £5 or £10, and its own maximum per transaction and per day. Your bank applies ceilings of its own underneath, and Google applies device level ceilings on top, which vary by issuer and by region. If a deposit fails despite a comfortable balance, the cause is usually one of those upper layers rather than the wallet itself.
Deposits are also instant in a way that can mislead. The zero hour bar in the chart is real, but it only describes money going in. Budget the exit with the 48 hour card settlement figure instead, and read the cashier's withdrawal page before depositing, because the available exit rails are listed there and they differ more between cashiers than the deposit menus ever do.
How these cashiers compare on paper
The table below lines up cashiers that support wallet deposits, grouped by what each is known for and, more importantly, by what stands behind each one. It is a paper comparison of behaviour and paperwork, and the licence column is the one to read twice.
| Casino | Licence | Market focus | What it is known for | UK protections |
|---|---|---|---|---|
| Midnite | UKGC licensed | UK-led brand | App-led sign up with a modern cashier | Self-exclusion, ADR, segregated funds |
| MrQ | UKGC licensed | mobile-led brand | Wallet deposits behind a short deposit menu | Self-exclusion, ADR, segregated funds |
| Betway | UKGC licensed | global bookmaker | Polished apps and a wallet-first cashier | Self-exclusion, ADR, segregated funds |
| BoyleSports | UKGC licensed | bookmaker | A simple cashier with wallet options | Self-exclusion, ADR, segregated funds |
| LiveScore Bet | UKGC licensed | media-led bookmaker | App-first flows with quick deposits | Self-exclusion, ADR, segregated funds |
| talkSPORT BET | UKGC licensed | media-led bookmaker | A mobile cashier running on wallet rails | Self-exclusion, ADR, segregated funds |
| Parimatch | UKGC licensed | international bookmaker | App-led cashier under a UK licence | Self-exclusion, ADR, segregated funds |
| Kwiff | UKGC licensed | UK bookmaker | A compact, mobile-first cashier | Self-exclusion, ADR, segregated funds |
| Bet UK | UKGC licensed | UK-led brand | A simple deposit menu with wallet support | Self-exclusion, ADR, segregated funds |
| Ivy Casino | UKGC licensed | licensed casino | A small-brand cashier taking wallet deposits | Self-exclusion, ADR, segregated funds |
| Donbet | No UK licence | offshore-facing casino | Crypto-friendly cashier with card deposits | None of the UK protections |
| Rolletto | No UK licence | offshore-facing brand | High-limit tables and crypto rails | None of the UK protections |
The pattern worth noticing is that the design notes and the licence column move independently. An app-led onboarding flow and a modern cashier say nothing about what happens when a dispute needs a third pair of eyes, while the rows marked as having no UK licence carry none of the protections in the last column, whatever their cashier offers. Wallet support is common ground across the table. The safety net behind the wallet is where the rows genuinely part company, and that is a question of paperwork rather than of design.
What the licence buys you
A UKGC licence is a bundle of specific, enforceable things. First, self-exclusion. Enrol once through the national scheme and every GB licensed operator must exclude you for the term you choose, from six months to five years. Sites without a UK licence sit outside that scheme entirely, so an exclusion you set there does not follow you to them.
Second, independent dispute resolution. If a licensed cashier declines a withdrawal and you disagree, you can take the case to an approved alternative dispute resolution body, free of charge, and the operator is bound by the outcome. It is the difference between arguing with the shop and having an adjudicator. A cashier operating without a UK licence offers no equivalent. Complaints go where its own terms point, under whatever framework it answers to elsewhere.
Third, money handling. Licensed operators must state how customer funds are protected, with segregation from business assets at a rated level, so a shortfall at the company does not automatically become a shortfall in your balance. Above all of it sits a regulator who can act on complaints, fine, suspend or revoke, which is what turns written rules into consequences.
Stated plainly: offers without a UK licence carry none of that. No self-exclusion coverage, no independent adjudicator, no fund protection rating, no regulator with power over the operator. The cashier can be polished and the wallet can work perfectly, and the structural position is still that you are dealing with the operator alone.
If gambling stops feeling like a choice, the National Gambling Helpline on 0808 8020 133, run by GamCare with BeGambleAware, is free to call, and GamStop self-exclusion at gamstop.co.uk reaches every GB licensed operator in a single enrolment.
Google Pay casino questions, answered
Can I withdraw to Google Pay?
Usually not. The wallet sits on the deposit side of the cashier, and most rulebooks route withdrawals back to the underlying debit card instead, or to a separate e-wallet if you have added one. That is why the model prices a card settlement at 48 hours: the exit rail is the card, not the wallet, so it pays to plan the exit before depositing.
Does a Google Pay deposit count for bonuses?
In most rulebooks it does, because the cashier sees a tokenised Visa or Mastercard debit transaction rather than a named wallet. Exclusion clauses usually list Skrill, Neteller and similar e-wallets by name, and Google Pay does not appear on those lists. The safe habit is to read the payment terms for the clause that governs eligibility, since the deciding factor is the card behind the wallet.
Are there fees for Google Pay deposits?
Google charges nothing for the service, and licensed cashiers do not add a fee to deposits, so the transaction posts to your debit card as an ordinary purchase. The real cost of a deposit is not on the rail at all. It sits in the wagering requirement, which the model puts at forty times the bonus, roughly £800 of stakes on a £20 match.
Why do payouts take so much longer than deposits?
A deposit is a single push that the wallet confirms in seconds. A payout is a different machine. The cashier runs an approval window the model averages at 6 hours, then the money moves through card settlement cycles. The model prices a debit card arrival at 48 hours, the midpoint of a 24 to 72 hour band, and no wallet setting can shorten either stage.
Does Google Pay work on iPhone as well as Android?
Android is where the wallet behaves fully, either in apps or through the Chrome payment sheet in a mobile browser. On iPhone the equivalent rail is Apple Pay, and many cashiers run both sheets side by side. If you switch devices, the important detail does not change: whichever sheet you use, the underlying debit card is what the cashier records and what the terms apply to.
What is the approval window exactly?
It is the stretch between you pressing withdraw and the cashier releasing the payment, and it is where most of the waiting hides. Reviews can be routine, or they can involve identity, payment-source and affordability checks. The model takes 6 hours as an average for this part of the market, but weekends, large sums and first withdrawals can push it well past that.
Are offshore-facing casinos that take Google Pay worth using?
Some offshore-facing casinos accept card-form wallet deposits, and the cashier can feel identical to a licensed one. The difference is not the rail, it is the paperwork. Without a UK licence there is no national self-exclusion coverage, no independent adjudicator for disputes and no requirement to segregate customer funds. Treat those sites as unregulated from a UK standpoint and weigh that before depositing anything.
Do Google Pay deposits affect my deposit limits?
The limits that matter are the ones the cashier sets, and they apply to a deposit whatever sheet you pay through, so using the wallet does not raise them. Typical minimums sit around £5 to £10, with operator ceilings above and your bank's own ceilings underneath. You can usually set a daily or monthly cap in the safer gambling area, and that cap follows the account, not the rail.