pay by phone casino
Pay by Phone Casino: How Carrier Billing Works and What It Omits
Phone billing puts a small stake on the bill in seconds; the model below shows where the payouts go instead.
The shortlist, before the detail
The board below carries this month's featured offers with their headline terms. The prose that follows models offers of this kind and never repeats those figures; the operator's own page is always the binding version.
Roulette King picks
Top roulette offers this month
The shortlist first, then the arithmetic. Four featured packages carry the headline terms below; the rest of the page models what offers of this kind usually cost and what a licence would have added.
Terms checked at the October 2026 review · 18+ · T&Cs apply. Offers move often: the operator’s own page is always the binding version.
- 1
 Night Luck82/100Casino welcome bonus 805% up to €6,400 + 280 FS
- MuchBetter · VISA · Apple Pay
- Crypto welcome 140% up to 1,600 USDT
- VIP pack 800% up to €14,500
Visit siteNight Luck18+ · T&Cs apply - 2
 EliteSpin80/100Welcome bonus €/£5,000 + 500 FS
- MuchBetter · NETELLER · MasterCard
- Lootboxes up to €/£20,000 or 500 FS
- BGaming festival: €80,000 prize pool
Visit siteEliteSpin18+ · T&Cs apply - 3
 Winbeast78/100Welcome pack €5,000 + 500 FS + €650 free bet
- MasterCard · Litecoin · MuchBetter
- Code FORTUNE: wheel on €40+ deposits
- Monday boost: 40% up to €300 (BOOST1)
Visit siteWinbeast18+ · T&Cs apply - 4
 Betportal75/100Welcome package 300% up to €/£1,000 + 150 FS
- Trustly · Bitcoin · Bank transfer
- 1st deposit: 150% up to €/£500 + 100 FS
- 2nd deposit: 100% up to €/£300 + 50 FS
Visit siteBetportal18+ · T&Cs apply
Placements on this board are paid, and the order is part of that arrangement. Featured brands hold no UK Gambling Commission licence, so GamStop, independent dispute resolution and segregated-funds rules do not reach them. Gambling can be addictive. Play responsibly. How we are paid.
How phone billing works
A pay by phone casino starts at the cashier rather than at the bank. You pick the phone billing option, choose from the short menu of amounts the brand allows, and confirm the charge, often with a code sent by text message. From there the money never touches a card. The charge is added to your monthly mobile bill, or taken straight away from pay-as-you-go credit if you run your handset that way, and specialist billing intermediaries sit between the brand and the networks to make the handshake work. That middle layer is why the flow feels almost identical from one brand to the next, even where the casinos themselves share nothing else. Deposits on this rail start small by design, and the cashier sets the exact minimum and maximum alongside the menu.
Caps are built into the rail rather than bolted on afterwards. Per-transaction ceilings commonly sit around £10, and daily ceilings vary by network and by brand, which means two players on different networks can face different limits at the same cashier. Treat those figures as typical of this part of the market rather than universal, because the deposit menu is the only version that counts: it shows exactly what your account and your network will allow before you confirm anything. The arithmetic stays deliberately plain. If the per-transaction cap is £10 and you want £30 of play, that is three separate confirmations, three text messages and three deliberate decisions rather than one open-ended card entry, and each pause is a chance to stop. Networks also differ in how they present the charges, so a glance at your bill after the first deposit is a sensible habit.
That friction is the design, not a flaw. Phone billing was built for small stakes: a few spins at £0.20 on the commute, a £1 bingo ticket in a lunch break, a modest top-up while the kettle boils. Because the rail cannot carry large amounts, it cannot carry large mistakes either, and because no card details are typed, stored or reused, there is nothing to mislay at the checkout. For players who keep one debit card purely for payouts and let the handset handle the deposits, the split works as a budgeting tool as much as a payment method. It also explains why the brands that lean on the rail tend to be mobile-led or bingo-led, because their whole product is built around short, small and frequent sessions.
Placement matters too. Among the deposit options at a typical GB-licensed brand, phone billing sits beside debit cards, e-wallets and the occasional prepaid voucher, and each rail answers a different question. Cards are the all-rounders, wallets are the speed merchants, and vouchers suit players who want to buy a fixed amount of play in advance. Phone billing answers a narrower question: how do I move a small, capped amount without touching a card at all? Players who recognise the question usually recognise whether the answer fits them, and the rest of this page is about what happens once it does.
The three-rail model
The model below treats pay by phone at GB-licensed brands as a deposit-only rail operating under the mobile carrier frameworks, with small per-transaction caps and no route back to the handset for withdrawals. Payouts always travel another way, which is why the phone row gets nothing in the payouts column. Fee lines are set to none across all three rails as a modelling assumption rather than a promise: most GB-licensed brands do not charge for taking a deposit this way, but networks can treat billing charges in their own fashion, so the cashier and your network's terms are where a rail gets confirmed as genuinely free. The model is deliberately spare: three rails, five columns, and assumptions stated in plain sight rather than buried.
| Rail | Deposit route | Model fee | Payouts | Notes |
|---|---|---|---|---|
| Phone billing | Charged to the mobile account | None | Not supported | Deposits only, so payouts need a bank rail added later |
| Debit card | Card entry | None | 1 to 3 working days | The standard payout route |
| E-wallet | Wallet balance | None | Under 24 hours | Needs a funded wallet |
Read the rows together and the shape of the model becomes obvious. Phone billing is the fastest way in and no way out: it moves money onto a balance in seconds but cannot take it off again, so every session funded this way ends at a different screen. The debit card row carries the payout weight at most brands, with 1 to 3 working days as the model's assumption for a standard withdrawal, while the e-wallet row shows the faster lane, under 24 hours, for anyone content to fund a wallet first. Whichever route you choose, the withdrawal rail has to be added and verified before it will pay anything, and verification at GB-licensed brands normally means proof of identity and proof that the method belongs to you.
Choosing between the two payout rails is mostly a question of speed against simplicity. A debit card payout needs nothing beyond the card itself, but the model's 1 to 3 working days counts working days rather than weekends, so a Friday request can land midweek. An e-wallet pays faster, under 24 hours on the model, yet the wallet has to be opened, funded and verified first, and some players find it becomes one more account to look after. Both routes beat waiting on a rail that does not exist, which is the position anyone lands in if they deposit by phone and only think about payouts afterwards.
How the brands compare
Cashiers differ more than front pages do, so the table below sorts this part of the market by licence, market focus and the way each brand treats the pay by phone rail.
| Casino | Licence | Market focus | What it is known for | UK protections |
|---|---|---|---|---|
| MrQ | UKGC licensed | mobile-led brand | phone billing as a first-class deposit rail | Yes, full scheme |
| Pub Casino | UKGC licensed | UK brand | simple cashier with phone billing | Yes, full scheme |
| Ladbrokes | UKGC licensed | high-street brand | card-first cashier with mobile options | Yes, full scheme |
| Coral | UKGC licensed | mainstream brand | card defaults with a mobile flow | Yes, full scheme |
| William Hill | UKGC licensed | high-street heritage | app-first cashier | Yes, full scheme |
| Sun Bingo | UKGC licensed | tabloid-partnered bingo | small-stake mobile deposits | Yes, full scheme |
| Foxy Bingo | UKGC licensed | bingo-led brand | mobile-first bingo cashier | Yes, full scheme |
| Heart Bingo | UKGC licensed | bingo-led brand | small-stake mobile play | Yes, full scheme |
| Gala Bingo | UKGC licensed | bingo-led brand | daily promotions on mobile | Yes, full scheme |
| 32Red | UKGC licensed | long-standing casino brand | mobile app with a compact cashier | Yes, full scheme |
| Kinghills | No UK licence | offshore-facing casino | phone billing rarely supported at this end of the market | None |
MrQ and Ladbrokes show the split at its widest. The mobile-led brand treats phone billing as a first-class deposit rail, so billing the handset sits at the front of the cashier instead of hiding among the alternatives, while the high-street brand runs a card-first cashier with mobile options attached, which suits players who deposit by card and mainly want an app that behaves on a small screen. Between those poles sit the bingo-led brands, where small-stake mobile deposits are the everyday habit rather than a headline feature.
Where the payouts go instead
Because the phone rail is deposits-only, every withdrawal needs a second rail, and that rail has to exist before the first payout will move. The reason is structural rather than a matter of brand choice: mobile billing was built for one-way charges, so a network can add an amount to a bill but has no mechanism for paying money back out through the handset. In practice that means a debit card in your own name, with 1 to 3 working days as the model's figure for a standard withdrawal, or an e-wallet, where the model assumes under 24 hours once a withdrawal is approved. Some brands also support a direct bank transfer payout, which follows the same verify-first rule, and where it is offered the transit time usually resembles the card figure. The details have to match as well: GB-licensed brands pay back to verified methods, which usually means identity documents and, on a first withdrawal, a short wait while the payments team checks the paperwork. Sorting that out on day one, rather than on the day you want to cash out, is the simplest way to keep a small win from sitting in limbo.
Two clocks run on any withdrawal, and only one of them belongs to the rail. The first is the brand's own processing window, the gap between your request and the payment being sent, which GB-licensed brands publish in their terms and which can stretch over a weekend. The second is the rail's transit time, the 1 to 3 working days on a card or the under 24 hours on a wallet in the model. Add the two together before deciding a payout is slow: a Friday evening request processed on Monday and sent to a card means arrival between Tuesday and Thursday on the model's assumptions. None of that changes with the deposit method used, which is worth remembering the next time a phone-funded balance feels a long way from the bank.
This is the quiet trade-off at any pay by phone casino: the easiest way in is never the way out, and the model is drawn that way on purpose.
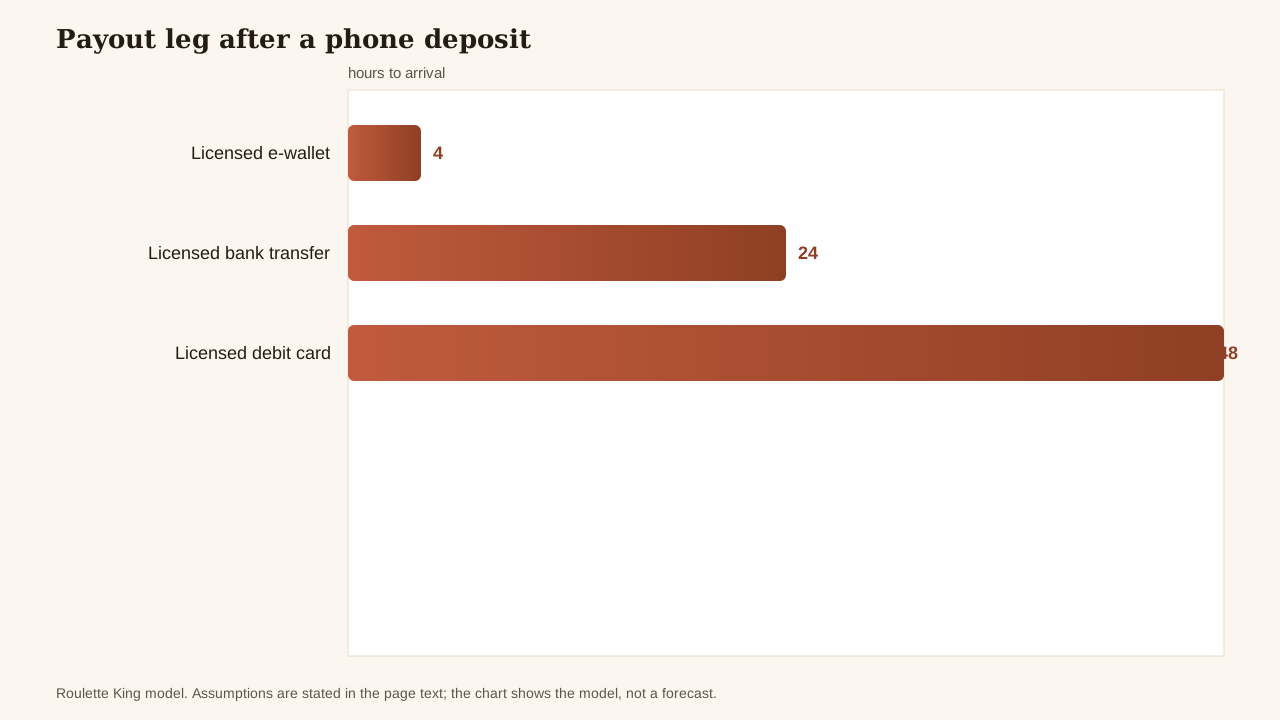
Once a payout rail exists, the other half of the maths is the terms attached to the deposit, and the wagering calculator below turns a stake, a multiple and a game weighting into a number you can plan around.
Wagering calculator
Turnover before withdrawal, modelled from the bonus and the multiple the terms set.
Model illustration with stated inputs; the terms of a specific offer always override a model.
Assume a £10 deposit carrying a 30x wagering rule, with slots counting in full toward the total: 30 multiplied by £10 is £300 of qualifying play, and at an average stake of £0.50 a spin that is 600 spins before the balance unlocks. Drop the average stake to £0.25 and the same rule asks for 1,200 spins, which shows how much the stake size matters next to the deposit size. Change any input and the arithmetic changes with it, and that is the point of running the numbers before you commit rather than after.
Caps, spend control and small-stake budgeting
Caps are the rail's defining feature, and they arrive from two directions at once. The network sets one ceiling, typically a fixed daily figure for charges to your account, and the brand sets another through the deposit menu it offers, with per-transaction amounts commonly sitting around £10. Contract customers face a further practical limit, because billing charges can only push a monthly bill so far before the network stops adding to it, while pay-as-you-go players are limited by the credit actually sitting on the handset. Both ceilings are enforced before the money moves, which is what separates a cap from advice. None of these numbers are universal, so treat every figure here as typical of this part of the market and let the deposit menu on your own account settle the question.
Pay-as-you-go and contract players budget differently on this rail, and it helps to know which one you are. A pay-as-you-go handset can only spend the credit it holds, so the phone itself becomes a prepaid budget: top up £15, and £15 is the hard boundary. A contract customer bills against a monthly account, so the useful boundary is the network's cap for gambling charges rather than the credit balance, and it is worth looking that figure up once and writing it down. Either way, the money spent on play sits on the same bill or balance as everyday spending, which makes the habit harder to hide from yourself, and that visibility is a feature rather than an inconvenience.
The arithmetic of a capped rail is worth running once. Assume a £10 per-transaction cap and a £30 daily ceiling on your network: two transactions spend £20, a third would take the day to £30, and a fourth would simply be refused. Roll the same logic across a week and a £10-a-day habit becomes £70, which is either exactly what you meant to spend or a signal that the in-account deposit limits need tightening too. Those limits sit alongside the rail's own caps rather than replacing them: say a £10 transaction ceiling inside a £50 weekly deposit limit inside a £200 monthly budget, three independent ceilings where the strictest one that applies is the one you feel, each enforced before the money moves rather than after.
Small rails suit budgeting for a second reason that has nothing to do with limits. Because the phone cannot receive payouts, winnings always leave through a slower, verified route, and that pause does useful work: it separates the impulsive moment of a deposit from the considered act of a withdrawal, and it hands you a natural point to decide whether the balance is play money or savings. Keep one card for payouts, let the handset handle the stakes, and the two halves of the hobby never blur into each other. Add the brand's own tools, such as session reality checks, time-outs and in-account limits, and the capped rail becomes one layer in a stack rather than the only line of defence. The whole appeal of a pay by phone casino, for careful players at least, is that the small scale is enforced by plumbing rather than by willpower.
What the licence buys you
A UK Gambling Commission licence is the difference between a regulated cashier and an unregulated one, and the benefits are concrete rather than decorative. Registration with GamStop, the national self-exclusion scheme at gamstop.co.uk, covers every GB-licensed online gambling brand at once, so one decision excludes you everywhere it matters. Complaints that stall with a brand can be escalated to an independent adjudicator, free of charge, instead of ending in a deadlock. Customer funds sit under regulator rules on segregation, which protects deposits if an operator runs into trouble. Above all, there is a regulator who acts on complaints, audits the games, and can fine or revoke a licence when a brand steps out of line.
Checking a licence takes moments and needs no paperwork. Every GB-licensed operator appears on the regulator's public register, and brands usually link to it from the footer of their own site, so a claim of being UKGC licensed can be tested in about a minute. The register also shows the trading names a licence covers, which matters where a familiar brand name sits on a different licence to the one you assume, and treating hidden licensing details as a reason to slow down costs nothing.
Offers without a UK licence carry none of that: no GamStop coverage, no independent dispute route, no assurance that customer funds are segregated, and no regulator to write to when something goes wrong. The final row of the comparison table marks that end of the market, and it is no coincidence that phone billing is rarely supported there. The rail is built on GB carrier frameworks and the consumer rules that surround them, so an offshore-facing casino has neither the plumbing nor the oversight to offer it properly, and where a similar method does appear without a UK licence, the caps, the verification checks and the protections do not travel with it.
If play ever stops feeling like a choice, two routes cost nothing and work straight away. The National Gambling Helpline on 0808 8020 133, run by GamCare with BeGambleAware, is open around the clock and takes calls from players and from worried family members. GamStop registration at gamstop.co.uk takes effect across GB-licensed brands once confirmed, and it cannot be undone on a whim, which is precisely why it works. Neither route demands a story or an excuse, only a decision.
Pay by phone casino questions, answered
How do pay by phone deposits work?
You choose the phone billing option in the cashier, pick an amount from the short menu on offer, and confirm the charge, often with a code sent by text message. Nothing card-shaped is involved: the money is added to your monthly mobile bill or deducted immediately from pay-as-you-go credit, with billing intermediaries handling the handshake between the brand and the network. Both contract and pay-as-you-go handsets work, with the bill or the credit doing the accounting in each case, and the balance updates as soon as the confirmation lands.
Can you withdraw to your phone bill?
No. The rail is deposits-only at GB-licensed brands, so payouts travel by a different route entirely, most often a verified debit card in 1 to 3 working days or an e-wallet in under 24 hours on the model's assumptions. Add and verify the payout method early, because a first withdrawal usually carries identity checks before anything moves, and a rail added in a hurry is the usual reason a balance sits in limbo.
What are the caps?
Per-transaction ceilings commonly sit around £10, with daily ceilings that vary by network and by brand, so treat these figures as typical rather than as rules. The deposit menu on your own account shows the exact amounts available to you before you confirm anything, and that menu always beats any general figure printed anywhere else.
Does it cost anything?
The model in this guide assumes no fee on any rail, and most GB-licensed brands do not charge for taking a deposit this way. Check two places regardless: your network's terms, because a few handle billing charges differently, and the brand's payments page, because an assumption in a table is not a promise. If a charge you did not authorise ever appears on a bill, raise it with the network first, since the billing relationship sits with them.
Which brands support it?
Support is a cashier question more than a brand-type question. Mobile-led and bingo-led names such as MrQ and Sun Bingo lean on small-stake mobile deposits, where a £1 ticket and a £10 cap sit comfortably together, while card-first cashiers at the high-street brands keep phone billing as one option among several. At any pay by phone casino, the definitive answer is the deposit menu on your account, and it is worth checking before you plan a session around the method.
Is it available outside the UK scheme?
Rarely. The rail runs on GB carrier frameworks, so offshore-facing casinos seldom support it, and where a similar method does appear without a UK licence, the caps, the verification and the consumer protections do not follow. The last row of the comparison table marks that end of the market, which is a statement about where the rules reach rather than a verdict on every operator within it.
What does the licence gap mean?
No GamStop coverage, no independent dispute resolution, no assurance of segregated funds and no regulator who acts on complaints, so a stalled withdrawal or a disputed balance would have nowhere to go. UKGC licensed brands carry the full scheme, and brands without a licence carry none of it. If play is becoming a worry, the National Gambling Helpline on 0808 8020 133 is free to call and always open, and GamStop registration at gamstop.co.uk covers the licensed market in one step.