independent casinos not on gamstop
Independent Casinos Not on GamStop: Who Runs Them and What Is Missing
Independent brands run their own rules and carry none of the scheme; the model below lines up both sides.
The shortlist, before the detail
The board below carries this month's featured offers with their headline terms. The prose that follows models offers of this kind and never repeats those figures; the operator's own page is always the binding version.
Roulette King picks
Top roulette offers this month
The shortlist first, then the arithmetic. Four featured packages carry the headline terms below; the rest of the page models what offers of this kind usually cost and what a licence would have added.
Terms checked at the October 2026 review · 18+ · T&Cs apply. Offers move often: the operator’s own page is always the binding version.
- 1
 Night Luck82/100Casino welcome bonus 805% up to €6,400 + 280 FS
- MuchBetter · VISA · Apple Pay
- Crypto welcome 140% up to 1,600 USDT
- VIP pack 800% up to €14,500
Visit siteNight Luck18+ · T&Cs apply - 2
 EliteSpin80/100Welcome bonus €/£5,000 + 500 FS
- MuchBetter · NETELLER · MasterCard
- Lootboxes up to €/£20,000 or 500 FS
- BGaming festival: €80,000 prize pool
Visit siteEliteSpin18+ · T&Cs apply - 3
 Winbeast78/100Welcome pack €5,000 + 500 FS + €650 free bet
- MasterCard · Litecoin · MuchBetter
- Code FORTUNE: wheel on €40+ deposits
- Monday boost: 40% up to €300 (BOOST1)
Visit siteWinbeast18+ · T&Cs apply - 4
 Betportal75/100Welcome package 300% up to €/£1,000 + 150 FS
- Trustly · Bitcoin · Bank transfer
- 1st deposit: 150% up to €/£500 + 100 FS
- 2nd deposit: 100% up to €/£300 + 50 FS
Visit siteBetportal18+ · T&Cs apply
Placements on this board are paid, and the order is part of that arrangement. Featured brands hold no UK Gambling Commission licence, so GamStop, independent dispute resolution and segregated-funds rules do not reach them. Gambling can be addictive. Play responsibly. How we are paid.
What independent means, in plain terms
Independent casinos not on GamStop are gambling sites that sit outside the two structures most British players assume arrive as standard. The first structure is corporate: an independent brand is not part of a big group, so it does not share a cashier, a complaints desk or a bonus catalogue with a roster of sister sites. The second structure is regulatory: the brand holds no UK licence, so it is not authorised by the Gambling Commission, and because the national self-exclusion scheme is tied to British licensing, it is not part of GamStop either. Both halves of that definition are structural facts rather than marketing labels, and both carry consequences that are easy to feel and difficult to undo.
In day-to-day terms, independence shapes nearly everything about how a site runs. The operator writes its own terms and conditions, sets its own deposit and withdrawal limits, chooses which game studios to aggregate, and decides, largely on its own authority, how complaints are answered. Lobbies on independent sites are frequently assembled from several aggregators at once, which is why two brands that look similar on the surface can behave completely differently once an account is open. Cashiers follow the same logic: one brand may lean on cards and wallets, another on crypto, and neither is bound by the payment standards that apply to a British licensee.
The cost side of independence is the part this page keeps returning to, because it is the part advertising tends to blur. When a brand operates outside the UK system, three protections fall away together. There is no GamStop coverage, since the scheme binds only operators licensed for Great Britain. There is no independent arbitration, because access to an adjudicator is a condition of a UK licence, not a courtesy extended at the operator's discretion. And there is no requirement to segregate player funds, because that rule is also written into licence conditions. Whatever an offshore regulator requires in place of these protections varies by jurisdiction and is generally lighter, and the difference lands on the player at the worst possible moment, which is when something has already gone wrong.
None of this makes an independent site automatically poor and none of it makes a licensed group automatically good; it describes where responsibility sits. With a licensed group, responsibility is shared with a regulator, a technical standards body and an adjudicator. With an independent brand, responsibility is concentrated in a single place: the operator itself. Readers weighing up independent casinos not on GamStop should treat that last sentence as the entire argument in miniature. Everything that follows, from the comparison to the model to the cashier arithmetic, is that sentence expanded with examples.
Side by side: independent brands and licensed operators
The comparison below brings together independent casinos not on GamStop and operators licensed for Great Britain, not to rank them but to show row by row what changes when a site leaves the British system. Two points are worth making before the table. First, the licence column is the hinge for everything else: wherever it reads no UK licence, the protections column follows automatically, and no wording in the market focus column changes that. Second, bonuses of this kind are marketed heavily across this part of the market, which is exactly why the final column deserves reading before anything else does. The table describes structures as they stand in late 2026, not reputations.
| Casino | Licence | Market focus | What it is known for | UK protections |
|---|---|---|---|---|
| Kinghills | No UK licence | offshore-facing casino | independent brand outside the UK scheme | none: outside the UK scheme |
| NineWin | No UK licence | offshore-facing casino | gamified independent lobby | none: outside the UK scheme |
| Donbet | No UK licence | offshore-facing casino | independent crypto-friendly cashier | none: outside the UK scheme |
| Goldenbet | No UK licence | offshore-facing casino | casino and sportsbook under one roof | none: outside the UK scheme |
| Rolletto | No UK licence | offshore-facing brand | independent high-limit brand | none: outside the UK scheme |
| Mystake | No UK licence | offshore-facing casino | broad independent lobby | none: outside the UK scheme |
| Roobet | No UK licence | crypto-native casino | independent originals | none: outside the UK scheme |
| Gamdom | No UK licence | crypto-first casino | independent community play | none: outside the UK scheme |
| JackpotCity | No UK licence | offshore-facing brand | long-running independent lobby | none: outside the UK scheme |
| Bet365 | UKGC licensed | sportsbook-first giant | the licensed contrast: group protections | GamStop across the group, arbitration, segregated funds |
| 888 Casino | UKGC licensed | long-running standalone casino | the licensed contrast: arbitration and segregation | GamStop, independent arbitration, segregated funds |
| All British Casino | UKGC licensed | licensed casino | the licensed contrast: UK-themed with full protections | GamStop, arbitration, segregated player funds |
Set Kinghills and 888 Casino beside each other and the pattern in the rows becomes concrete. Kinghills is presented to the market as an offshore-facing casino, an independent brand outside the UK scheme, which means a complaint about a delayed withdrawal travels up the operator's own support chain and stops there. 888 Casino, described in the table as a long-running standalone casino, offers the licensed contrast: arbitration and segregation are conditions of holding a UK licence, so a player unhappy with the answer can carry the dispute to an adjudicator the operator does not employ. Neither row is a review and neither is a recommendation. They are two ways of structuring a casino, and the structure determines who holds power when a payment is late or a term is contested.
A model of the market: protections by brand type
The model below reduces the market to two shapes and asks what each shape provides by default. The assumptions are stated openly. It reflects the structure of the market as it stood in October 2026. It treats big licensed groups as operators running several Great Britain-licensed brands under common ownership, with shared platforms and a single complaints pathway. It treats independent offshore-facing brands as casinos without a UK licence that nonetheless attract British players, whether through search results, affiliate pages or word of mouth. Nothing in the model is a claim about any individual operator; it describes what each structure requires, not what every operator chooses to add on top.
| Feature | Big licensed groups | Independent offshore-facing brands |
|---|---|---|
| Self-exclusion | GamStop across the group | none |
| Dispute route | independent arbitration | none |
| Player funds | segregation required | not required |
| Lobby depth | shared catalogues | mixed feeds |
| Payout rails | GBP debit rails | cards, wallets, crypto |
The rows should be read as a set rather than as separate trivia. A self-exclusion that stops at the brand boundary, a complaints process that ends where the operator's own staff sit, and money that may sit alongside operating costs are three expressions of one underlying fact: outside the licence, nothing is mandated. Lobby depth and payout rails matter differently. Shared catalogues versus mixed feeds is mostly an experience question, although mixed feeds can slow an answer when a game round is queried, because a third-party aggregator now sits between the player and the studio. Payout rails shape both cost and recourse, which is the subject of the cashier section further down the page.
What independence removes
Independence is easiest to grasp by subtraction. Place a licensed operator and an independent one next to each other, then remove everything that exists on the licensed side only because a licence demands it, and what remains is a fair picture of the offshore-facing market.
The scheme goes first. GamStop is one registration that closes every GB-licensed online operator simultaneously, and an independent brand is untouched by it by definition. A person who excluded themselves through the scheme and later opens an account with an offshore-facing site has not found a gap in the scheme; they have walked out of the area the scheme covers, and the scheme cannot follow. That is worth stating without softening, because the search term suggests some readers are looking precisely for that boundary.
Arbitration goes next. Licensed operators must provide access to an independent dispute resolver, so a contested withdrawal, a voided bet or a bonus dispute can be judged by someone with no stake in the outcome. Independent brands carry no equivalent obligation. Their complaints pages describe internal escalation steps, and the final decision on most matters belongs to the operator. Fund segregation goes with it: under UK conditions, customer money must be held apart from operating funds, while the independent model imposes no such requirement, so a deposit may sit in the same pool as marketing spend if the operator's arrangements allow it.
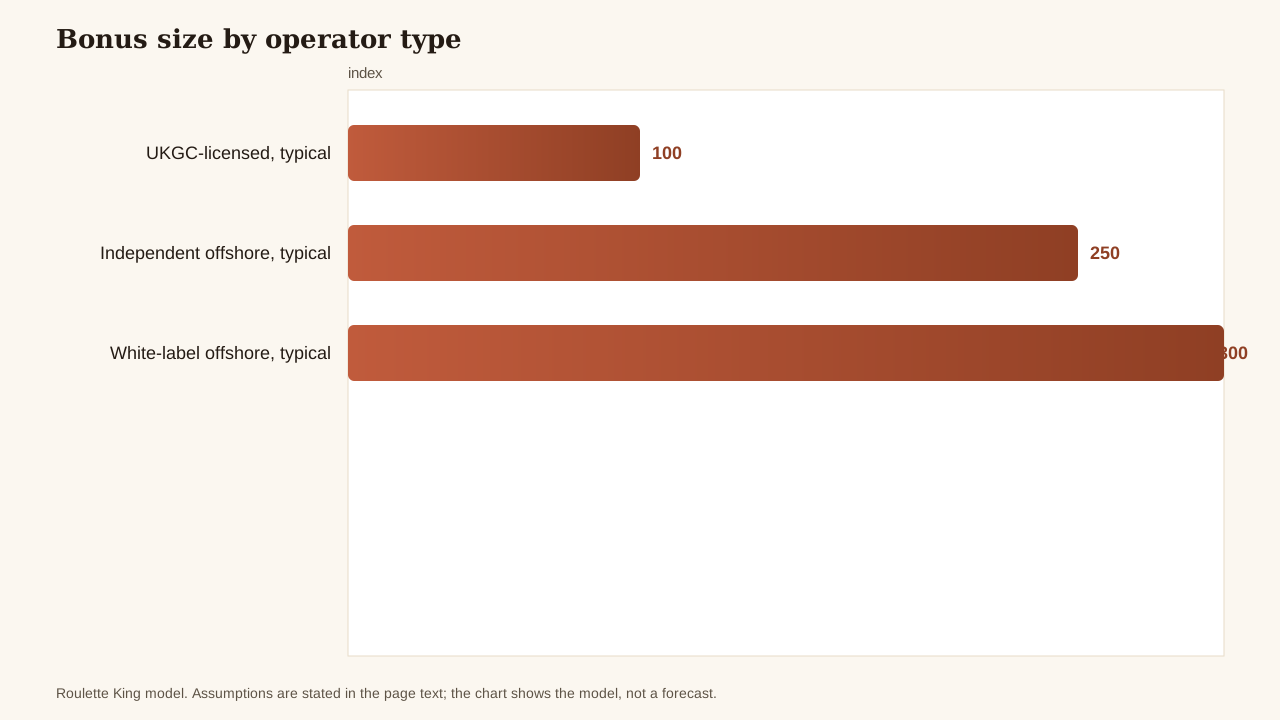
Smaller removals follow the three large ones. Deposit limits on an independent site are policed by the site itself rather than audited by a regulator. Affordability checks may never trigger. Advertising follows the operator's own code rather than an enforceable one. And the entity with statutory power over a UK-licensed brand, the Gambling Commission, has no authority over an offshore-facing one at all. None of these removals is hidden; each sits in the terms and conditions for anyone who reads them. The model in the figure below compresses the same comparison into a single view.
If percentages are hard to feel, the working below translates the same assumptions into pounds and pence.
Effective bonus cost calculator
Deposit, match and multiple turned into credited money, turnover and a modelled cost.
Model illustration with stated inputs; the terms of a specific offer always override a model.
How independent cashiers differ
A licensed British cashier is deliberately narrow: debit cards, bank transfer where offered, a short list of approved wallets, everything settling in pounds. Independent cashiers are wider and rougher. Cards are processed by offshore acquirers, often under descriptor names that mean nothing at a glance on a statement. Wallets arrive and disappear. At brands described as crypto-friendly or crypto-first, the conversion question moves from the bank to the player, along with the timing and the fees that come with it.
The arithmetic of that wider cashier is worth doing once, slowly, with the assumptions visible. Suppose a player moves £250 onto an independent site, and the wallet conversion carries a spread of 1.2% with a processor fee of 0.9%. The friction before a single spin is £250 × (1.2% + 0.9%), which is £5.25. Those percentages are illustrative rather than quoted from any operator: real spreads vary with the currency pair, the processor and the hour, and some brands show no visible fee at all while recovering the cost of the rail elsewhere.
Now suppose the session ends and the player requests £400 back, with the brand applying a 1% cashout fee under its published terms. The fee is £4.00. Converting back at the same assumed 1.2% spread costs a further £4.80. The round trip, £5.25 out and £8.80 back, has cost £14.05 in total, which is about 2.2% of the £650 moved across the cycle. Every figure depends on the assumptions just stated. The exact pennies are not the point; the point is direction. On independent cashiers, cost per movement is a genuine variable, while a standard withdrawal on a licensed debit rail costs the player nothing on the payment itself.
Speed follows a similar shape. Licensed sites typically publish windows running from instant to within three working days once a request is approved, because established debit rails handle the last mile. Independent brands list windows that stretch from a few hours to several days, then add processor time, then, for crypto, network confirmations that nobody at the casino controls. Those ranges come from the operators' own published terms rather than from any test, and they can change without notice.
Identity checks deserve a paragraph of their own, because their absence up front is sometimes presented as a convenience. It is not convenience; it is timing. Offshore brands can and do request documents at the withdrawal stage, and a check that arrives after a win lands far harder than one that arrives at registration. A cashier that asks no questions before a deposit and several after a withdrawal has not removed friction. It has relocated it, to the exact moment a player least wants it.
The licence, the scheme and where the line sits
A licence buys specific, enforceable things. When an operator holds a UK licence, funds rules require customer money to be segregated. Complaints rules require access to an independent adjudicator. Technical standards govern how games are tested and how systems behave. Advertising rules bind how offers are presented to British audiences. Participation in GamStop is mandatory, which is the connective tissue between the licence and the player's own off switch. If any part of that framework fails, there is a regulator with statutory powers to investigate, fine, suspend or revoke.
GamStop does something narrower and faster. The scheme is free and takes minutes to use. A registration closes online gambling accounts with every operator licensed for Great Britain at once. The terms available are six months, one year or five years. An active exclusion cannot be lifted early; once the minimum term ends, the scheme's own process governs renewal or release. The scheme's website is gamstop.co.uk. Because membership is tied to British licensing, an offshore-facing brand cannot join, which is the technical reason the brands described on this page sit outside it and the honest reason a scheme registration will not close an account held with one of them.
The helpline is the human layer underneath both. The National Gambling Helpline on 0808 8020 133, run by GamCare with BeGambleAware, is free and open every day of the year. Trained advisers take calls from people worried about their own gambling and from people worried about somebody else's. They can talk through self-exclusion, bank-level blocking, longer-term support and what to expect from each, without judgement and without selling anything. Of every number and address on this page, it is the one worth keeping.
An honesty note closes the section. Nobody needs independent casinos not on GamStop in order to keep gambling, whatever the search terms imply. If the appeal of the phrase is that a scheme entry is standing in the way, the scheme is doing exactly what it was set up to do, and the right next step is a conversation with the helpline rather than a hunt for a site the scheme cannot see.
What is an independent casino?
It is a site that is not part of a big group and holds no UK licence, which places it outside GamStop automatically. It writes its own terms, sets its own limits, aggregates its own game feeds and answers complaints through its own staff. The phrase independent casinos not on GamStop describes that whole combination: independent structure, offshore-facing operation, no connection to the British self-exclusion scheme. It is a description of a business shape, not a mark of quality, and the shape determines what happens when something goes wrong.
Do these brands take part in GamStop?
No. They cannot, in fact, because the scheme is open only to operators licensed for Great Britain. A brand with no UK licence has no mechanism for joining, whatever its promotional pages imply. Where a site claims to honour the scheme, read the wording closely: what it usually offers is an internal exclusion tool that the site itself controls, which is a different creature entirely, since the operator can amend its own tool while the scheme sits beyond any operator's reach.
What protections go missing?
Three large ones, then several smaller ones. The scheme itself, which would otherwise close licensed accounts across the market at once. Independent arbitration, which would otherwise give a disputed withdrawal somewhere to go besides the operator's own inbox. Segregated player funds, which would otherwise keep deposits ring-fenced from operating costs. Beyond those: games tested against UK technical standards, advertising under enforceable rules, affordability checks that can be triggered from outside the operator, and a regulator holding real statutory powers. Independence removes the lot in one stroke, because every item on that list exists as a condition of the licence.
How do payouts compare?
On licensed sites, a standard withdrawal to a debit card typically settles within one to three working days once approved, with no charge on the rail itself and a complaints route if it stalls; those figures are typical published timescales, not promises. Independent brands publish wider windows, sometimes a few hours and sometimes several days, and then conversion spreads, processor fees or cashout charges depend on the method chosen. Crypto cashouts move quickly when networks are quiet and slowly when they are not. The deeper difference is not speed but recourse: a stalled licensed payout can be taken to an adjudicator, while a stalled independent payout has an escalation chain that ends inside the company.
Who can help when a dispute has no arbiter?
Start with the National Gambling Helpline on 0808 8020 133, which is free and open every day; advisers cannot adjudicate a casino dispute, but they can advise on the practical steps that remain. For a payment problem specifically, the card issuer's own processes apply regardless of where the casino is licensed: raise the matter with the bank or card company, provide timestamps, receipts and correspondence, and respond to their queries quickly. Keep a complete record of everything the casino says as well. There is no UK arbiter for an offshore-facing brand, so the issuer's processes and the operator's internal escalation are usually what is left.
Is there a way around self-exclusion?
No, plainly. Nothing here exists to defeat an exclusion, an ISP block, a payment block or an identity check, and attempting to get round one only undermines a protection that was put in place for a reason. If an exclusion is doing its job and the urge to slip past it has arrived, that is the moment to call the National Gambling Helpline on 0808 8020 133. Advisers can talk through what is happening, suggest blocking and banking tools that operate across the whole market, and help plan the next stretch of the exclusion. The helpline is the right route, it is free, and it answers every day.
Where can I get help?
The National Gambling Helpline on 0808 8020 133, run by GamCare with BeGambleAware, is free, confidential and open every day of the year. GamStop, at gamstop.co.uk, sets or extends an exclusion across all GB-licensed online operators. GamCare provides longer-term support, including structured help for people whose gambling has moved beyond their control. Advisers at the helpline can also point towards local services where that is useful. None of it depends on which kind of casino a person has been using; the line takes the call either way.