mastercard casino
Mastercard casino
Credit gambling has been banned in Britain since April 2020; the card that works is a debit one, and the model prices its pace.
The shortlist, before the detail
The board below carries this month's featured offers with their headline terms. The prose that follows models offers of this kind and never repeats those figures; the operator's own page is always the binding version.
Roulette King picks
Top roulette offers this month
The shortlist first, then the arithmetic. Four featured packages carry the headline terms below; the rest of the page models what offers of this kind usually cost and what a licence would have added.
Terms checked at the October 2026 review · 18+ · T&Cs apply. Offers move often: the operator’s own page is always the binding version.
- 1
 Night Luck82/100Casino welcome bonus 805% up to €6,400 + 280 FS
- MuchBetter · VISA · Apple Pay
- Crypto welcome 140% up to 1,600 USDT
- VIP pack 800% up to €14,500
Visit siteNight Luck18+ · T&Cs apply - 2
 EliteSpin80/100Welcome bonus €/£5,000 + 500 FS
- MuchBetter · NETELLER · MasterCard
- Lootboxes up to €/£20,000 or 500 FS
- BGaming festival: €80,000 prize pool
Visit siteEliteSpin18+ · T&Cs apply - 3
 Winbeast78/100Welcome pack €5,000 + 500 FS + €650 free bet
- MasterCard · Litecoin · MuchBetter
- Code FORTUNE: wheel on €40+ deposits
- Monday boost: 40% up to €300 (BOOST1)
Visit siteWinbeast18+ · T&Cs apply - 4
 Betportal75/100Welcome package 300% up to €/£1,000 + 150 FS
- Trustly · Bitcoin · Bank transfer
- 1st deposit: 150% up to €/£500 + 100 FS
- 2nd deposit: 100% up to €/£300 + 50 FS
Visit siteBetportal18+ · T&Cs apply
Placements on this board are paid, and the order is part of that arrangement. Featured brands hold no UK Gambling Commission licence, so GamStop, independent dispute resolution and segregated-funds rules do not reach them. Gambling can be addictive. Play responsibly. How we are paid.
Debit only: what April 2020 changed about the card
On 14 April 2020, operators licensed in Great Britain stopped accepting credit cards for gambling. The rule covered the whole account rather than one product: slots, table games, live dealer tables and sports stakes all moved onto debit, and the cashier stopped treating credit as an option at all. Any Mastercard casino description that still talks about staking on credit in Britain is describing a market that closed years ago, and the wording printed on the card now matters more than the network logo on the front.
The change followed a review of gambling with borrowed money, and it landed on the licensed market all at once rather than brand by brand. Before it, a credit card looked like any other rail at the checkout; after it, the practical question moved from whether a deposit would work to which card in the wallet carries the word Debit. Prepaid and charge products sat in a grey area for a time, and the settled position is that licensed cashiers run on debit cards and the rails built around them, with everything else either adapted or turned away.
Why, then, do some sites still advertise card deposits that include credit? Because the rule binds operators licensed in Great Britain, and it does not travel with the card. An offshore-facing brand serving other markets can accept a Mastercard credit card without breaking the rules that apply to it, since those rules were written somewhere else entirely. That is the tell rather than a loophole: a cashier still offering credit for stakes is a cashier operating outside the British scheme, and the licence section near the end of this page covers what that absence costs.
What the ban did not change is worth stating too. Debit deposits still appear in the balance straight away at licensed cashiers, the card still sits at the front of every wallet, and nothing about the rule slows a deposit down. The change was about the source of the money rather than the speed of the pipe, which is why the argument about cards in Britain has moved almost entirely to the withdrawal side of the ledger.
The practical effect showed up in household budgets as much as in cashiers. Stakes on a debit card can only ever draw on money already in the account, so the rail itself became a quiet brake on chasing. That is a description of the plumbing rather than a claim about outcomes: a card with no credit line cannot spend credit, however the session feels at half past midnight.
For everyday purposes the phrase has narrowed accordingly. A search for a Mastercard casino in Britain now resolves to a debit cashier, and the useful questions are about pace and protection: how quickly the rail pays back, and who stands behind it when something goes wrong. Those two questions shape everything that follows.
The model: how each version of the card behaves
The April 2020 ban sits in a statutory rule rather than in any operator's house policy, which is why every licensed cashier in Britain changed on the same day, and the detail in this model was checked in October 2026. Read the rows as pricing rather than as a recommendation. Debit is the standard rail, carrying stakes at no model fee and returning payouts in one to three working days. Credit has nothing to price because there is no service: a Mastercard casino cannot offer it, whatever the card in your pocket says. Maestro rides the same rails as debit where it is issued, and prepaid Mastercard products vary, because a voucher-style card frequently cannot receive a payout at all.
| Rail | Stakes allowed under UK rules | Model fee | Payout arrival | Notes |
|---|---|---|---|---|
| Mastercard debit | yes | none | 1 to 3 working days | the standard rail |
| Mastercard credit | banned for gambling since April 2020 | n/a | n/a | not available at licensed brands |
| Maestro | yes | none | 1 to 3 working days | where issued |
| prepaid Mastercard | varies | none | payouts need a bank rail | voucher-style products |
Two details deserve a second look. The fee column reads none on every row because licensed operators do not charge for card deposits; the cost of the card is measured in time instead, which is why the payout column carries the weight. The n/a entries in the credit row are not a gap in the model. They are its finding: a rail that is banned for gambling has no fee to price and no payout window to wait for, because a licensed brand cannot send money down it in either direction.
Using the rows is deliberately simple. Match the card in your wallet to a row, read across for the stakes answer, then down the columns for fee and pace. Where the model says varies, the position depends on the exact product and the exact brand, and the cashier of a licensed operator states it plainly before any money moves. The model is deliberately narrow as well: it prices the card, not the brand, and the brand-level position always lives in the cashier and the terms.
The card across the market: licence first
A Mastercard casino comparison starts with the licence column, because licensing and cashier habits separate this part of the market more cleanly than any headline offer does.
| Casino | Licence | Market focus | What it is known for | UK protections |
|---|---|---|---|---|
| Betfred | UKGC licensed | bookmaker with a card-first cashier | debit rails as the default | Yes, full scheme |
| Ladbrokes | UKGC licensed | high-street brand | card deposits and app payouts | Yes, full scheme |
| Coral | UKGC licensed | mainstream brand | card defaults | Yes, full scheme |
| William Hill | UKGC licensed | high-street heritage | app payouts to debit | Yes, full scheme |
| Betfair | UKGC licensed | exchange and sportsbook | card rails beside the exchange wallet | Yes, full scheme |
| BoyleSports | UKGC licensed | bookmaker | simple card cashier | Yes, full scheme |
| PartyCasino | UKGC licensed | casino-first brand | card and wallet rails | Yes, full scheme |
| 32Red | UKGC licensed | long-standing casino brand | card deposits with published terms | Yes, full scheme |
| NetBet | UKGC licensed | established casino | card bonuses with terms | Yes, full scheme |
| Magic Red | UKGC licensed | licensed casino | broad card support | Yes, full scheme |
| Grosvenor Casinos | UKGC licensed | casino-chain brand | card deposits to the club brand | Yes, full scheme |
| JackpotCity | No UK licence | offshore-facing brand | card deposits outside the UK scheme | None |
Betfred and JackpotCity mark the two ends of the split: Betfred runs a bookmaker with a card-first cashier, debit rails as the default, inside the full UK protection scheme, while JackpotCity takes card deposits outside the UK scheme. The identical plastic behaves differently once the licence changes, because access to self-exclusion, independent dispute resolution and a regulator all hinge on where the operator is licensed rather than on the network printed on the card. The card itself is neutral; the licence is not. Everything else in the comparison follows from that column.
Payouts: the price of the rail, paid in time
The model prices a Mastercard debit payout at one to three working days, and that window rests on three assumptions: the request went in before the operator's daily cut-off, account verification is already finished, and no weekend sits inside the wait. A request made on a Monday afternoon, on those assumptions, lands on the Wednesday at the two-day mark; the same request on a Friday afternoon waits until the middle of the following week, because Saturday and Sunday are not working time. Verification is the usual source of delay on a first withdrawal, so finishing that paperwork before requesting anything is worth an hour of admin.
Three things sit outside the window. The clock starts when the operator approves the withdrawal, not when the button is pressed, and approval can take a day on a first request while documents clear. Banks add their own processing at the far end, which is why two brands can quote the same window and still pay at different speeds. Weekends and bank holidays do not count towards it, so a five-day stretch on the calendar can be a two-day wait on the model.
The rail is closed-loop in practice. Card payouts return to the card used to deposit, which is simple until the card has expired or been replaced, at which point the money travels by a bank rail instead and the same journey takes longer. Wallets sit on the other side of the figure below: an e-wallet rail often settles within hours once the withdrawal is approved, and that speed is the main reason many players keep one alongside the card. The debit card remains the standard, though, because it is the rail most people already hold and the one every licensed Mastercard casino cashier supports.
Choosing between the two is mostly a question of what the wait is worth. A card payout costs nothing and arrives inside the model's window, which suits anyone not in a hurry; a wallet often arrives the same afternoon, which suits anyone who is. Neither rail usually charges at the licensed end, so the choice is about pace rather than price.
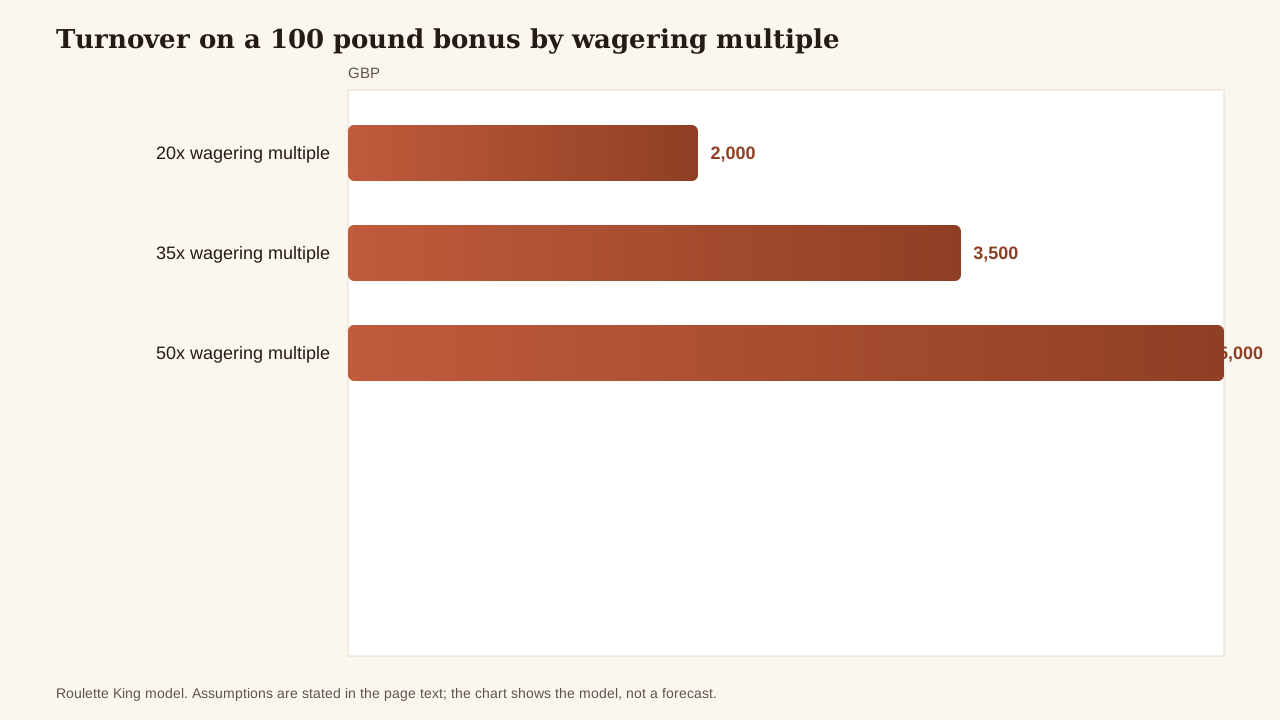
Bonuses price in the same currency, because qualifying stakes take time as well as money. A card-funded balance that has to be turned over a set number of times will sit in play for days on a busy week, and the multiplier, not the card, decides how many.
For that arithmetic, the wagering model below takes a deposit and a multiplier as inputs, and on its default assumptions of a £50 deposit at 35x it returns £1,750 of qualifying stakes before the balance unlocks.
Wagering calculator
Turnover before withdrawal, modelled from the bonus and the multiple the terms set.
Model illustration with stated inputs; the terms of a specific offer always override a model.
What the card adds, and what it does not
Debit chargeback is the card's genuine extra. Under Mastercard's scheme rules, a bank can raise a dispute when a payment went wrong in specific ways: an unauthorised transaction on the card, a deposit that never arrived in the account, a merchant that failed to deliver what was paid for. Unauthorised is the operative word, because money taken from a card without permission sits in a different category from money staked willingly, and that distinction decides most outcomes. In a gambling context the uses are narrow but real, and they start with a call to the bank that issued the card rather than with the operator's support queue, since the bank is the party that operates the mechanism.
The limits matter just as much as the mechanism. Chargeback is a scheme process rather than a statutory right, and the bank decides each case on the evidence in front of it. It is not a route to reversing stakes that were placed and settled, however the session ended, and a dispute raised without grounds tends to finish with the claim refused and the account closed at both ends. Prepaid products often sit outside the mechanism entirely. Records decide close cases: deposit receipts, timestamps and correspondence are what a dispute handler actually reads, so keeping them costs nothing now and can matter later.
The honest summary is that the card adds a narrow, evidence-dependent dispute route, while the licence adds the broad protections: self-exclusion, independent review of complaints and segregated balances. Neither returns money lost to the games themselves. Confusing the two, usually after a bad session, is the most common mistake people make with the chargeback process, and it ends in frustration more often than in refund. The card's job is to move money; the licence's job is to make the ground rules enforceable.
The licence: what it actually buys
A licence from the Gambling Commission is the difference between a cashier and a scheme, and it buys four things in particular. Access to GamStop, the national self-exclusion service at gamstop.co.uk, where one registration covers every licensed brand at once. Independent dispute resolution, so a complaint that stalls with the operator has somewhere else to go, with a decision that both sides are expected to honour. Segregated funds, so player balances are held apart from the operator's own money rather than sitting on its general ledger. And a regulator who acts on complaints, with powers that reach into the business rather than stopping at its inbox.
Offers without a UK licence carry none of it. There is no GamStop registration, so excluding yourself at one brand leaves the rest of that market open. There is no independent dispute route, so the operator's own word is usually the end of the line. There are no segregated funds, so a balance sits wherever the business puts it. There is no regulator obliged to act, only a foreign authority with its own priorities and its own working language, and some of those authorities are perfectly legitimate for the markets they serve; the point is that their reach stops at their own borders. A card deposit does not repair any of that, because the protections attach to the licence rather than to the plastic.
Help exists independently of any brand. The National Gambling Helpline, run by GamCare with BeGambleAware, is free and confidential on 0808 8020 133, and it is the right first call when play stops feeling like a choice. Licensed brands add their own tools on top, from deposit limits to time-outs and reality checks, and those tools only exist where the licence does, which is the quiet argument for reading a site's footer before its cashier. Checking takes seconds: the licence statement sits in the footer of a licensed site, and the public register on the regulator's site confirms it. That habit, unglamorous as it is, does more for a balance than any feature of the card itself.
Mastercard casino questions, answered plainly
Can you stake on a credit card in the UK?
No. Credit card gambling has been banned in Great Britain since April 2020, and the rule applies to every operator licensed here, across casino games, slots and sports. A site that still accepts credit for stakes is operating outside the British scheme, which says everything about its licence and nothing good about its protections.
How fast do Mastercard debit payouts arrive?
The model prices one to three working days, on the assumptions that the request beat the daily cut-off, verification is complete and no weekend falls inside the window. Verification, not the rail, is what usually slows a first payout. Wallets often settle faster once the withdrawal is approved; cards remain the standard because nearly everyone holds one, and nearly every licensed cashier supports them without fuss.
Do bonuses sometimes exclude card deposits?
Yes. Some offers of this kind restrict which deposit methods qualify, and individual cards or wallets are sometimes excluded in the terms. The terms decide the matter, so it is worth reading the qualifying-deposits line before staking rather than discovering it afterwards, when a withdrawal is already delayed and the balance is locked.
Is Maestro accepted?
Where it is issued, yes: Maestro rides the same rails as debit in the model, with no fee and the same one to three working day payout window. Issuance has narrowed over recent years, so the cashier is the sensible place to confirm the card works before building a deposit plan around it.
What about prepaid Mastercard options?
They vary by brand. Voucher-style products are sometimes accepted for deposits, and stakes are sometimes allowed where the product is verified, but a prepaid card frequently cannot receive a payout, so withdrawals need a bank rail instead. Treat prepaid as a spending tool rather than a payout rail, and expect the return journey to take longer than the outward one.
What is the chargeback reality?
Narrow and evidence-dependent. The mechanism exists for unauthorised transactions and payments that went wrong in defined ways, and the bank decides each case on its merits. It does not reverse settled losses, and prepaid products often sit outside it altogether. Receipts, timestamps and correspondence are what a dispute handler reads, so keep them from the first deposit onwards.
What does the licence gap actually mean?
No GamStop, no independent dispute resolution, no segregated funds and no regulator obliged to act on a complaint. The deposit still works, which is precisely the problem, because the money arrives while the protections do not. If play stops feeling like a choice, the National Gambling Helpline on 0808 8020 133 is free and confidential.